Need $100 fast in Canada? An instant loan app can front you a small amount of cash before your next paycheque, usually with no credit check and funds in minutes. The most affordable route is a cash advance app that charges 0% interest, instead of a payday lender that adds a fee to every $100 you borrow.
Bree is one option. It is an interest-free line of credit up to $750, with no credit check, sent by direct deposit to your bank account. Your limit is personalised, based on your income and bank history. This guide compares the main $100 instant loan apps in Canada, shows what each really costs, and explains how to get funds today without falling into a payday-loan trap.
Key Takeaways
- A $100 instant loan app fronts you cash before payday, usually with no credit check and approval in minutes. Approval is based on your income and bank history, not a credit score.
- Payday loans are the costly route. Federal rules cap them at $14 per $100 borrowed, which works out to roughly 365% APR on a two-week loan.
- Cash advance apps charge 0% interest. They make money from optional tips or an optional fee for faster funding, not from interest on what you borrow.
- Bree is an interest-free line of credit up to $750 with no credit check, sent by direct deposit to your bank account. It is free to use, and government benefits (ODSP, OW, CPP, CCB, EI) count as income.
- No app can truly "guarantee" approval. Any honest provider approves you based on steady income and consistent deposits, so approval is likely if you qualify, never guaranteed.

What Is a "$100 Loan Instant App" in Canada?
A $100 loan instant app is a mobile service that fronts you a small amount of cash, usually somewhere between $20 and $1,500, before your next paycheque. Approval is based on your bank account history rather than a credit check, and the money arrives electronically by e-transfer or direct deposit, depending on the app. These apps grew popular because they skip hard credit checks and move faster than a bank.
Cash advance apps differ from payday loans in Canada in a few key ways:
- 0% interest options. Many cash advance apps charge 0% interest, while payday lenders charge $14 per $100.
- Often no credit check. Many apps approve you on your bank account history without pulling your credit score or report.
- More flexible repayment. Instead of a payday loan's fixed next-paycheque due date, many apps let you repay on a schedule that fits your budget.
- No hidden fees. Clear pricing, with any fee shown before you accept.
Top Instant $100 Loan and Cash Advance Apps in Canada (2026)
Search "$100 loan instant app Canada" and you meet a long list of services. Below is a Canada-focused rundown of the main options, so you can see how they compare on limit, cost, and funding speed. Figures are current as of September 2026.
Bree stands out for three reasons. The limit is higher, up to $750 rather than the $250 that Nyble and KOHO Cover cap at, so one request can cover a real bill instead of a fraction of it. The cost is genuinely 0%, with no mandatory fee to borrow. And the money lands by direct deposit in your own bank account, so it is yours to move as you like.
Where Payday Loans Fall Short
Payday loans are the most expensive way to borrow $100 in Canada. Federal rules cap the cost at $14 per $100 borrowed, which the Financial Consumer Agency of Canada puts at an annual rate of roughly 365% on a two-week loan. The full balance is usually due on your next paycheque, and missing it can trigger extra fees and a rollover cycle that costs more than the original loan.
The fee stack around a payday loan matters too. According to the Financial Consumer Agency of Canada, a returned or bounced payment typically cost $45 to $48 at most banks, and as much as $50. Since March 12, 2026, a federal rule caps NSF fees at $10 at federally regulated banks. That cap lowers one common penalty, but it does nothing about the payday loan's own $14-per-$100 charge, which is where most of the cost still sits.
The Real Cost of a $100 Advance (Beyond "0% Interest")
A "0% interest" advance is not always free, so it pays to read how each app makes money. Most cash advance apps earn through one of three levers: a monthly subscription, a fee to fund your advance instantly, or an optional tip. Those costs are small next to a payday loan, but they are real, and stacking advances turns small fees into a habit.
US regulators, where these apps are studied more closely, have put numbers on it. The National Consumer Law Center, citing California regulator data, found that tip-based advance apps carried an average APR of 334% once the optional fees were counted, comparable to licensed payday lenders. The Consumer Financial Protection Bureau reported that roughly 90% of workers using paycheck-advance products paid at least one fee. The design is the same one sold in Canada, so the lesson carries: an advance is cheap per use and expensive as a routine.
Bree: An Interest-Free Line of Credit up to $750
Bree is a Canadian interest-free line of credit up to $750, built as an alternative to payday loans and overdraft fees. Here is what sets it apart:
- Up to $750, not just $100, so one request can cover a phone bill and groceries rather than a fraction of the gap.
- Never any interest. Zero interest, with optional tips in place of hidden fees.
- No credit check. Bree reviews your real bank account cashflow, not your credit score, so your credit history and credit report are never affected.
- Repay on your own schedule. You will see your terms before you accept, with no late fees and no penalties.
- All income types accepted. Employment income and government benefits (ODSP, Ontario Works, CPP, CCB, EI) both qualify as steady income.
- Direct deposit. Funds land in your own bank account, free in 1 to 3 business days, or in minutes for an optional express fee.
How to Get up to $100 From Bree
Requesting funds from Bree takes a few minutes, with no paperwork:
- Download Bree for iOS or Android, or sign up at trybree.com. You can apply from anywhere Bree operates in Canada.
- Connect your bank account through a secure, read-only connection. Bree cannot move money without your request, and it verifies your income without a credit check.
- Request up to $100 or any amount up to your personalised limit. Choose Express if you need the money in minutes.
- Receive funds by direct deposit to your bank account, in minutes with the optional express fee or in 1 to 3 business days for free.
- Repay on your own schedule. There are no late fees, and you can repay early with no penalty.
$100 Advance Cost-Savings Calculator
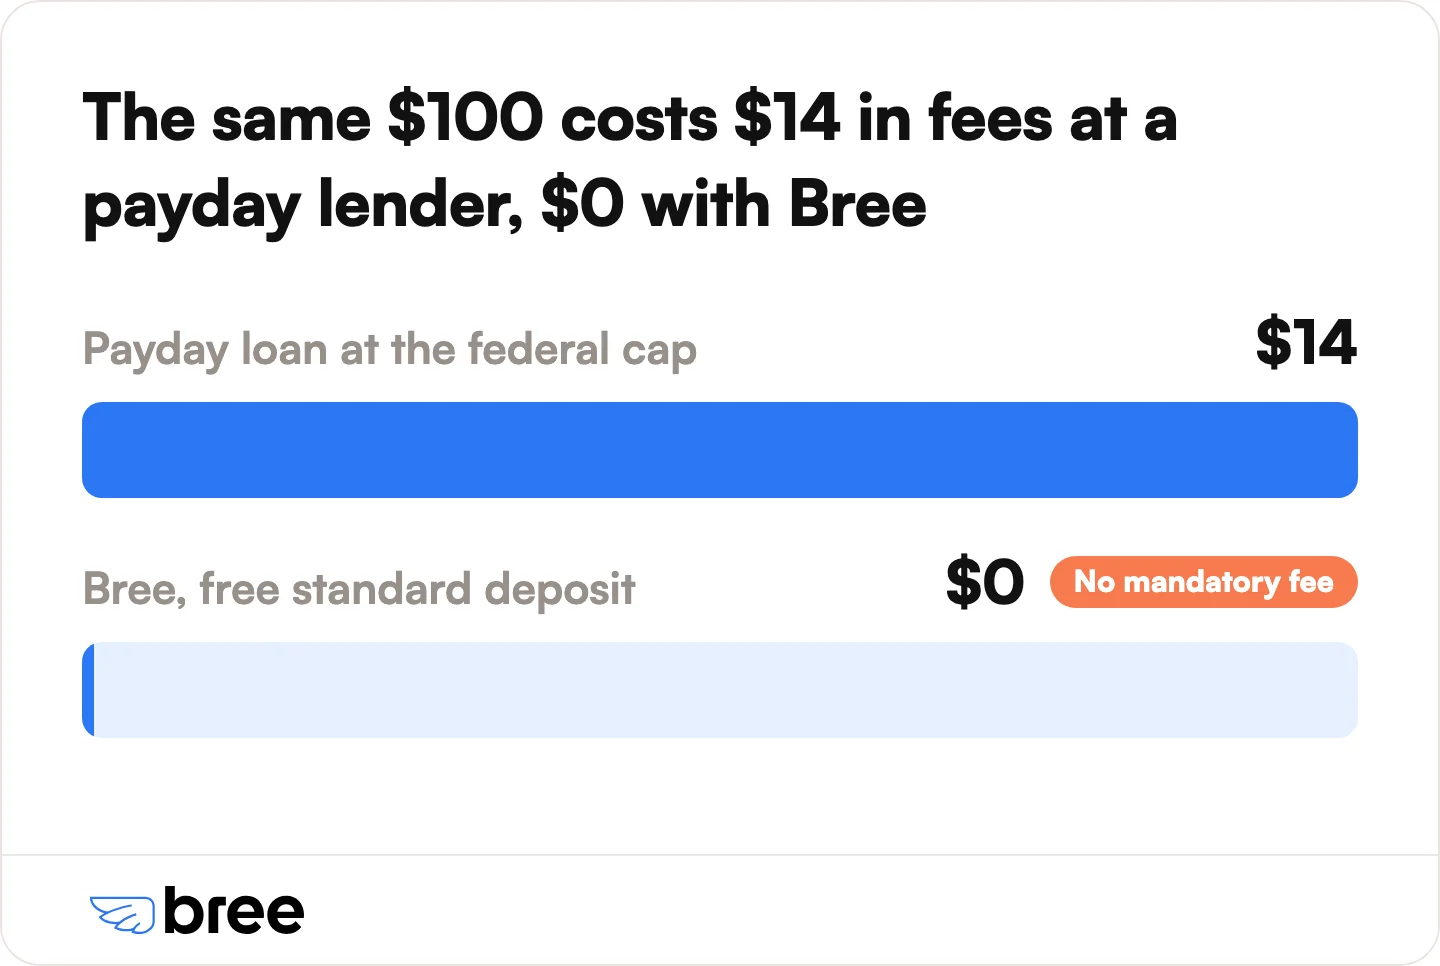
Use the calculator to compare what you would repay with Bree versus a payday loan at the federal cap. On a $100 advance, a payday loan at $14 per $100 costs you $14 in fees. The same $100 through Bree's free standard deposit costs $0, with an optional tip or express fee only if you choose to add one. The gap grows with every advance you take.
Who Qualifies for a $100 Instant Loan App in Canada?
Cash advance apps have simpler requirements than traditional lenders. To qualify for funds from Bree, you need:
- A Canadian bank account with at least two months of transaction history.
- Steady income of $1,200 or more per month, from employment or government benefits.
- Direct deposit history showing consistent income landing in your account.
- Age 18 or older, or the age of majority in your province.
- No minimum credit score. Bad credit or no credit history is fine, because there is no credit check.
Unlike many payday lenders that require employment verification, Bree reads your bank account history to confirm income. That makes approval more accessible for Canadians on non-traditional income, including government benefits that many competitors reject.
Payday Loans vs Cash Advance Apps: What's the Difference?
Many Canadians treat payday loans and cash advance apps as the same thing, but they work differently.
Payday loans in Canada:
- Cost: $14 per $100 borrowed, the federal cap.
- Rate: roughly 365% APR on a two-week loan.
- Repayment: due on your next paycheque, usually about 14 days.
- Access: apply online or in-store with a payday lender.
- Risk: high chance of a rollover debt cycle.
Interest-free cash advance apps:
- Cost: 0% interest, no mandatory fee, just an optional tip.
- Rate: 0% APR.
- Repayment: on your own schedule, not tied to a single payday.
- Access: apply in the app, funds sent by direct deposit to your bank account.
- Risk: lower, with no interest and more flexible repayment.
Not every instant loan app is interest-free. Some, like Pay2Day and Lenditt, still charge the payday-style $14 per $100. For most Canadians an interest-free app is the smarter choice. You get the cash you need for a small gap, receive it quickly, and pay no interest.
Is a $100 Instant Loan App Worth It?
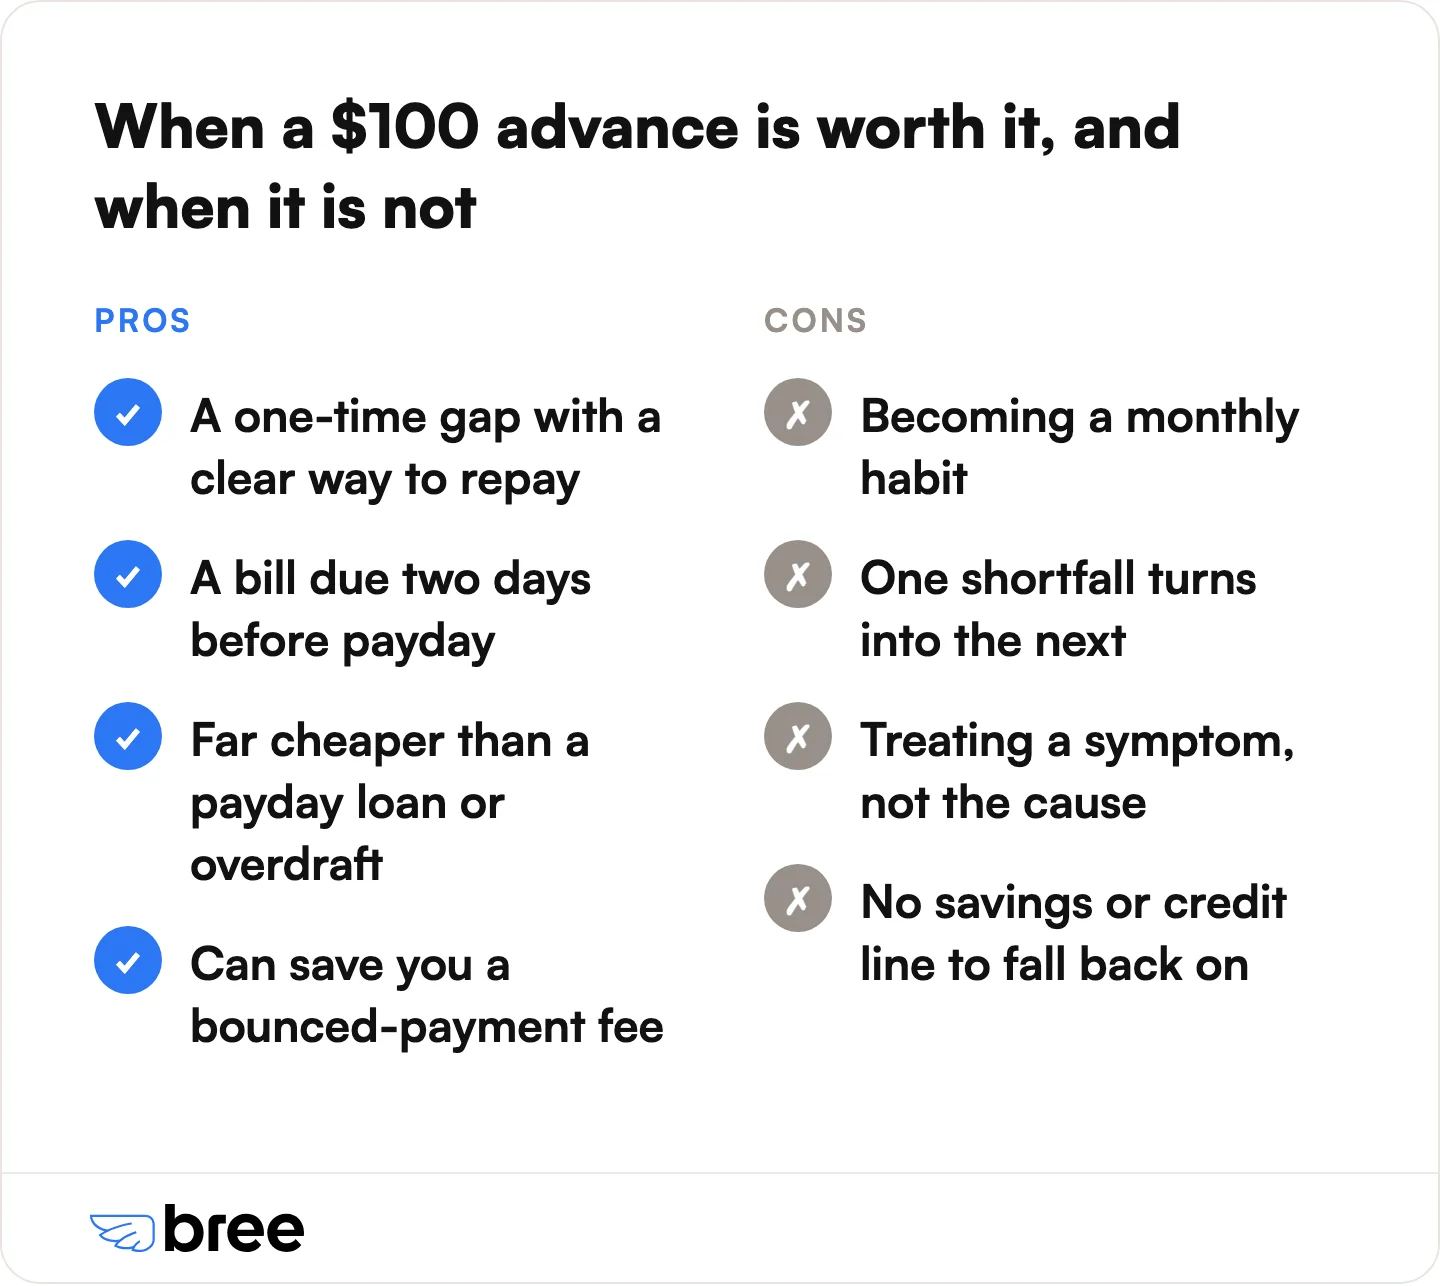
A $100 instant loan app is worth it when you have a one-time gap and a clear way to repay it, such as a bill due two days before payday. Used that way, a 0% advance is far cheaper than a payday loan or an overdraft, and it can save you a bounced-payment fee.
It works against you when it becomes a monthly habit. Someone reaching for a $100 advance usually has no line of credit or savings to fall back on, which is how one shortfall turns into the next. If you find yourself requesting an advance every pay period, the tool is treating a symptom, not the cause. A 0% app like Bree is still the least harmful option in that spot, but the real fix is closing the gap so you are not borrowing every month.
Frequently Asked Questions
What app will spot me $100 instantly in Canada?
Bree offers a line of credit up to $750, including $100 if that is all you need, with no credit check and funds by direct deposit to your bank account. You can request funds 24/7, and with the optional express fee the money arrives in minutes. Your limit is personalised to your income and bank history.
Does Bree do a credit check?
No. Bree does not run a credit check or pull your credit report. Approval is based on your income deposits and cashflow trends, so your credit score is never affected. That makes Bree a fit for Canadians with bad credit, thin credit files, or no credit history.
Can I get guaranteed approval for a $100 loan app?
No honest app can guarantee approval. Bree approves applicants who show regular income of at least $1,200 a month and steady deposits, so if you meet those criteria approval is very likely. Any service promising "guaranteed approval" regardless of income is a warning sign.
What happens if I can't repay on time?
Bree never charges late fees or sends your account to collections. If you are struggling, contact Bree's support team to work out your options. This is a major difference from payday lenders, who add penalties and may report unpaid debt to credit bureaus.
Can I get a cash advance on ODSP or disability benefits?
Yes. Bree accepts government benefits, including ODSP, Ontario Works, CPP, CCB, and EI, as qualifying income. Your benefits count the same as employment income for approval.
Is Bree available across Canada?
Bree is available to Canadians in most provinces. Availability can change, so check the app for your area before you apply. Wherever Bree operates, you can request funds online and receive them by direct deposit to your bank account.
How fast can I get the money?
With Bree's Express option you can get funds in minutes by direct deposit for an optional fee, and you can request them 24/7. The free standard deposit takes 1 to 3 business days. Either way, there is no branch visit and no waiting in line.
What if I have bad credit?
Bad credit is not a barrier. Because there is no credit check, your credit score and history do not affect approval. Approval depends on your income and your ability to repay, not your credit file.
The Bottom Line
If you need $100 today and want to avoid the payday-loan trap, a 0% cash advance app is the smarter choice. It is cheaper than a payday loan at $14 per $100, and it comes with real budgeting help instead of a rollover cycle.
Bree is the interest-free line of credit we built for Canadians between paycheques: up to $750, no credit check, no interest, and government benefits accepted as income. More than 600,000 Canadians use it, and it holds a 4.8 out of 5 rating on Trustpilot from over 8,000 reviews. Whether you need to cover a surprise bill, dodge an overdraft, or bridge the gap to payday, you can request funds in a few taps and get them by secure direct deposit.
Ready to skip the 365% APR? See how Bree's line of credit works or read real Bree reviews from Canadians who have used it.
Sources
- Financial Consumer Agency of Canada: Payday loans
- Financial Consumer Agency of Canada: New NSF fee regulations bring down the cost of banking
- National Consumer Law Center: Data on earned wage advances and fintech payday loan tips
- Consumer Financial Protection Bureau: Developments in the paycheck advance market

Join our newsletter to get the latest updates