Installment loans let you borrow a lump sum and pay it back in fixed payments over several months or years, at a rate that runs from single digits for the strongest credit up to Canada's 35% legal cap. Which lender is best matters, but the bigger decision is whether you need to pay interest at all for the amount you actually need. This guide compares the 10 best installment loans in Canada for 2026 by type, cost and who each one fits, then shows where an interest-free line of credit fits for smaller, short-term gaps.
We reviewed each lender's published terms, and we set them next to Bree, the interest-free option we build for Canadians who need a little help between paydays.
Key Takeaways
- Installment loan rates are capped at 35% APR as of October 2026. Canada lowered its criminal interest rate to 35% APR on January 1, 2025, so alternative lenders now run from single digits for strong credit up to that ceiling. Payday loans are exempt and still cost far more.
- Marketplaces and direct lenders solve different problems. Loans Canada, LoanConnect and Fat Cat Loans send one application to many lenders, while Spring Financial, easyfinancial and Fairstone lend to you directly.
- Bad credit and government-benefit income are accepted by several lenders, including Cashco Financial, Green Loans and Magical Credit, but the trade-off is almost always a rate near the 35% ceiling.
- Bree is the only option here that charges 0% APR. It also runs no credit check, so for gaps up to $750, an interest-free line of credit avoids the interest an installment loan adds on top of what you borrow.

Top 10 Installment Loans in Canada
Here is how the 10 lenders compare on type, loan size and credit requirements, with Bree shown first as the interest-free alternative. Every lender here operates under Canada's 35% APR cap; exact rates, amounts and terms shift often, so confirm the current figures a lender quotes you before you sign.
1. Spring Financial
Focus: a fully online direct-lender application. Spring Financial is a Vancouver-based direct lender that offers personal installment loans online across Canada. The whole process runs online, from application to funding, and approval can come the same day. If you do not qualify for a standard loan, Spring may offer its "Foundation" credit-builder product instead, where you receive the money only after completing all the payments. Read which product you are actually being approved for before you sign.
2. Loans Canada
Designed for comparing many lenders through one marketplace. Loans Canada is a loan-search platform, not a direct lender. It matches one application to a network of partner lenders across every province, and it works with good credit, bad credit and past bankruptcy. It was established in 2012. The trade-off of any marketplace is that your details are shared with several third-party lenders rather than one, which usually means more follow-up contact.
3. LoanConnect
Designed for pre-qualifying without an upfront credit hit. LoanConnect is an Ontario-based loan-search platform that returns multiple offers from one application, often within a day or two. You can see offers using a soft pre-qualification that does not affect your credit score, and borrowers of all credit types can apply. Like any marketplace, it is online only with no branches, and it can match you only to lenders in its network.
4. easyfinancial
Focus: larger amounts from a branch-based lender. easyfinancial, part of goeasy, is a national alternative lender with more than 400 locations plus an online application. It has offered installment loans for over 18 years, can approve in minutes, and gives borrowers 14 days to return a loan. It lends across the country, in sizes from small loans up to very large ones. The trade-off is cost: like most alternative lenders, its rates climb toward the 35% cap for weaker credit profiles.
5. Fairstone
Designed for a no-obligation quote. Fairstone has operated in Canada since 1923 and runs more than 230 branches. It offers both unsecured and secured installment loans in every province except Nunavut. You can apply online in minutes and get a quote using a soft credit check that does not affect your score, with funding in as little as one day. Two things to weigh: its rate floor sits above the cheapest options here, and it is geared toward borrowers who own their home.
6. Cashco Financial
Focus: flexible terms in Western Canada. Cashco Financial is an Alberta-based direct lender offering Flex installment loans with funding often within a day. It serves Alberta, British Columbia, New Brunswick and Saskatchewan only, and it accepts bad credit and several income types, including government benefits and private pensions. There are no fees to pay the loan off early, and it has store locations as well as online applications. Its rate sits near the 35% ceiling, so it suits borrowers who value flexible terms and benefit-income acceptance over the lowest cost.
7. Green Loans
Designed for small, short-term borrowing with no credit check. Green Loans is a short-term installment-loan broker operated by NCR Financial, in business for over 15 years. It arranges small-dollar loans with no credit check, so it is accessible with bad credit. It accepts a range of income types, including CPP, OAS, private and government disability, workers' compensation, the Canada Child Benefit and welfare. It is available in every province except Manitoba and Alberta. The cost is the catch: on top of interest it charges a broker fee, so the total cost of a small, short-term loan is higher than the headline rate.
8. Helium Loans
Designed for borrowers avoiding a payday loan. Helium Loans is a direct lender that positions itself as a payday-loan alternative, offering personal loans, short-term installment loans and lines of credit. It gives an instant decision and can defer a payment for up to 14 days with no fee. It is available everywhere except Quebec, and it requires employment, steady monthly income and a fair-or-better credit score. Two cautions: Helium does not publish its rate, so ask for the exact figure before committing, and its credit-score requirement means it is not an option for the weakest credit.
9. Magical Credit
Designed for bad-credit borrowers in Ontario. Magical Credit is a direct lender focused on borrowers with poor credit. Its installment loans are currently available only in Ontario, and it charges a fixed rate that sits just under the federal cap. For its personal loans, it accepts government-subsidy income such as EI, workers' compensation, maternity leave, the Canada Child Benefit and pensions as a secondary source, which helps applicants that banks reject. The rate near the 35% ceiling means it is built for approval odds, not for a low cost of borrowing.
10. Fat Cat Loans
Focus: same-day funding through a broker network. Fat Cat Loans is a loan-search platform that returns offers from one application, aimed at borrowers whose credit is less than perfect. It covers a wide range of loan sizes across Canada, with same-day funding available. Because it is a broker rather than a direct lender, your final rate depends on which network lender picks up your application, and you are limited to lenders in that network.
Before You Borrow: The Interest-Free Alternative
Every option above charges interest, and most top out near Canada's 35% ceiling. Bree is the interest-free line of credit we built for the Canadians an installment loan often overcharges: people who need a few hundred dollars to reach their next payday, not a multi-year loan. It offers up to $750 at 0% APR with no credit check.
Here is how a Bree line of credit compares with a typical installment loan:
- 0% APR, not 35%. A Bree line of credit charges no interest. You pay back what you draw, nothing more. Bree is free to use, and we make money from optional tips, like a waiter.
- No credit check. We look at your recent bank-account history, not your credit score, so a stressed or thin credit file does not rule you out.
- Direct deposit to your bank account. Standard delivery is free and lands in 1 to 3 business days. If you need it sooner, an optional express fee gets cash in minutes.
- Repay on your own schedule. Your repayment is not pinned to a single payday. You will see your terms before you accept.
- Government benefits count as income. ODSP, OW, CPP, CCB and EI all qualify, which many lenders will not accept.
For a $500 emergency, a $750 interest-free line of credit does the same job as a small installment loan without adding interest on top. More than 600,000 Canadians use Bree, which holds a Trustpilot score of 4.8 out of 5 from over 8,000 reviews. You can see how Bree works or read Bree reviews before you decide.

How to Choose an Installment Loan in Canada
The best installment loan for you depends on your credit, how much you need and how fast. Weigh these five factors before you apply.
APR and total cost
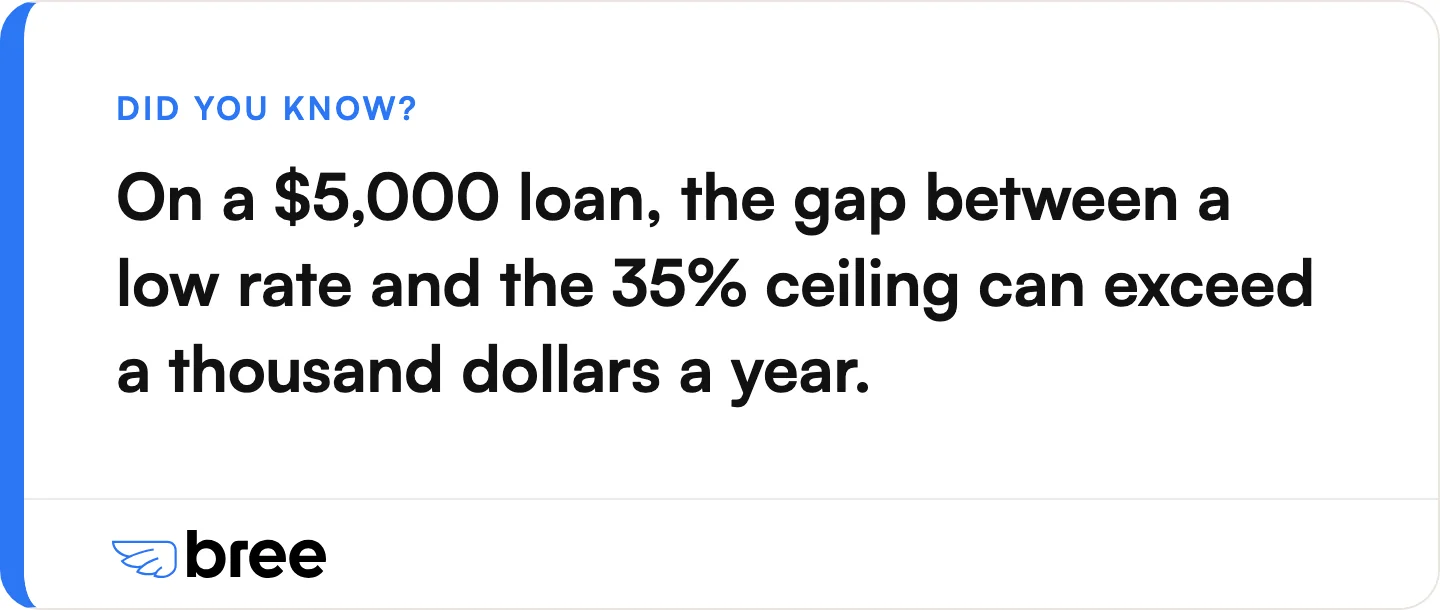
APR is the single biggest driver of what a loan costs. Since January 1, 2025, the most any non-exempt lender in Canada can legally charge is 35% APR (Department of Finance Canada). Borrowers with strong credit are offered the lowest rates, while bad-credit borrowers usually land near the 35% cap. On a $5,000 loan, the gap between a low rate and the 35% ceiling can exceed a thousand dollars a year. Payday loans are the exception: they are regulated province by province and cost far more, the equivalent of about 365% a year (Financial Consumer Agency of Canada).
Soft versus hard credit check
A soft credit check lets you see a quote or pre-qualification without affecting your score, while a hard check can lower it temporarily. Lenders like Fairstone and marketplaces like LoanConnect let you check offers with a soft pull first, which is worth using before you commit to a hard application.
Fees and the fine print
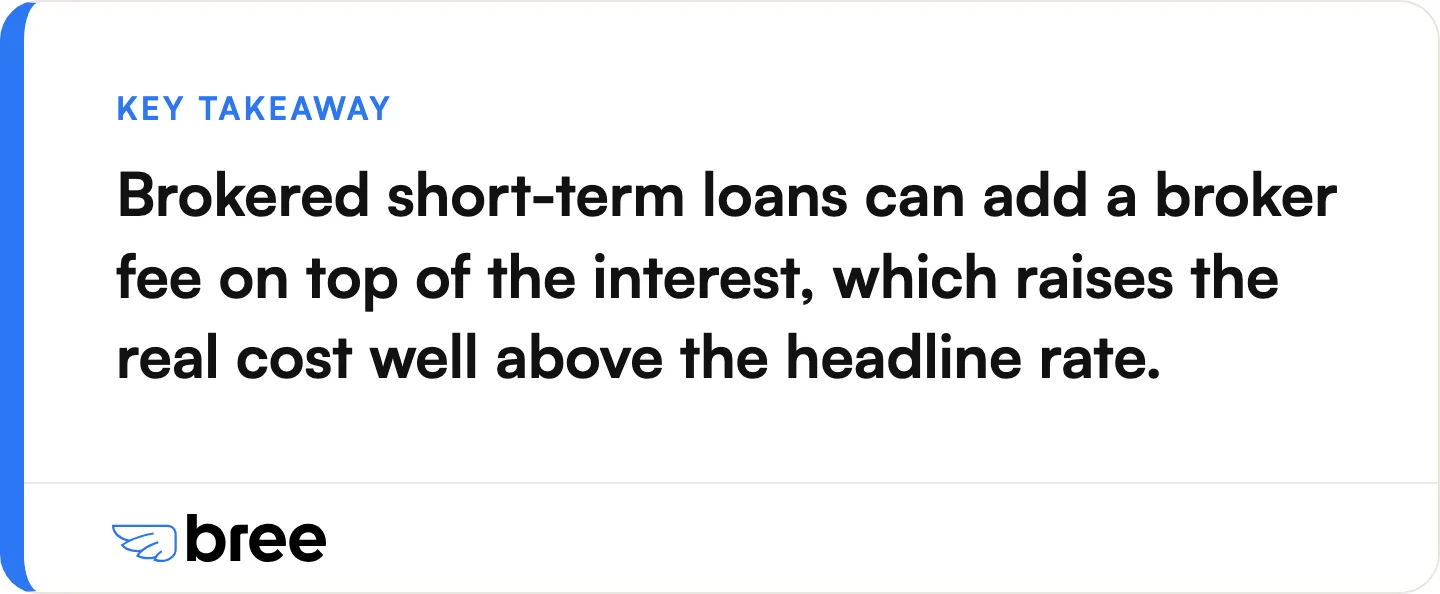
Read the agreement for origination charges, administrative fees, broker fees and prepayment penalties. Brokered short-term loans in particular can add a broker fee on top of the interest, which raises the real cost well above the headline rate. The best installment loans in Canada show transparent pricing with no surprise charges and no penalty for paying early.
Funding speed
If you need money quickly, favour online lenders and marketplaces, which often approve within hours and fund within one to two business days. Branch-based lenders can be slower but let you speak to someone in person.
Credit requirements and income
Banks and credit unions have strict credit requirements, while alternative lenders weigh current income and employment more heavily. If your income is a government benefit, check acceptance first: Cashco Financial, Green Loans and Magical Credit accept some benefit income, and a Bree line of credit accepts ODSP, OW, CPP, CCB and EI. Even with bad credit you may have options that focus on income rather than past credit mistakes.
Frequently Asked Questions
What is the difference between an installment loan and a payday loan?
An installment loan is repaid in fixed payments over months or years, while a payday loan is due in full on your next payday. Installment loans carry much lower rates. Since January 2025 they are capped at 35% APR, while payday loans are exempt from that cap and cost the equivalent of about 365% a year (Financial Consumer Agency of Canada).
Can I get an installment loan with bad credit in Canada?
Yes. Several Canadian lenders specialise in bad-credit installment loans, including Cashco Financial, Magical Credit and marketplaces such as Loans Canada and LoanConnect. They focus on your current income rather than your credit score, but the trade-off is an APR near the 35% ceiling. An interest-free line of credit with no credit check can be a lower-cost option for smaller amounts.
Can I get a 0% interest personal loan in Canada?
Traditional installment loans do not come at 0%, because interest is how lenders make money. The interest-free options are products built differently. A Bree line of credit charges 0% APR on up to $750 and makes money from optional tips instead of interest, which is why it fits small, short-term needs rather than large multi-year borrowing.
Do installment loans build credit?
They can. Most installment lenders report your payments to the credit bureaus, so paying on time can rebuild credit over time, while missed payments damage it. The initial application may involve a hard check that dips your score briefly. A Bree line of credit runs no credit check and does not report to the bureaus, so it neither helps nor hurts your credit.
How fast can I get an installment loan?
Many online lenders and marketplaces give an instant decision and deposit funds within one to two business days, and some advertise same-day funding. Branch-based lenders can take longer. For speed on a small amount, a Bree line of credit offers free standard direct deposit in 1 to 3 business days, or cash in minutes with an optional express fee.
What documents do I need to apply?
Most lenders ask for government ID, recent proof of income such as pay stubs or a tax slip, bank statements and proof of address. Having these ready speeds up approval. Marketplaces usually collect this once and share it with their partner lenders.
Conclusion
The best installment loan in Canada depends on your credit, the amount you need and how fast you need it, but almost all of them share one feature: an APR that can climb to the country's 35% cap. Comparing lenders on rate, amount and term, as this guide does, is the way to avoid paying more than you have to.
Before you take on an interest-bearing loan, it is worth asking whether you need one at all. For gaps up to $750, Bree is an interest-free line of credit built for Canadians between paydays, with 0% APR, no credit check and government benefits accepted as income. When the amount is small and short-term, skipping the interest is the smartest choice you can make. You can get started with Bree in a few minutes.
Sources

Join our newsletter to get the latest updates