Yes, you can often get an NSF fee refunded in Canada. Call your bank as soon as you spot the charge, explain what happened in a few plain sentences, and ask for a one-time courtesy reversal. Banks are not required to refund the fee, but they frequently will for a customer in good standing with a first-time or occasional slip. Your odds are best when you act fast, stay polite, and keep it factual.
There is also good news if a fee slips through. Since March 12, 2026, federally regulated banks in Canada cannot charge more than $10 for a non-sufficient funds (NSF) fee, down from the $45 to $48 that most big banks used to charge. This guide walks through how to get a fee reversed, what the new cap means, and how to stop these fees from happening again.
Key Takeaways
- Banks will often reverse an NSF fee as a one-time courtesy. Your best odds come from calling quickly, being in good standing, and asking politely for a single goodwill reversal.
- NSF fees are now capped at $10 at federally regulated banks. The cap took effect on March 12, 2026, replacing the $45 to $48 fees that were standard before.
- You cannot be charged an NSF fee twice in two business days, or at all when your account is short by less than $10. Both rules are written into the regulation.
- An NSF fee is not the same as an overdraft fee. An NSF fee means the bank declined the payment. An overdraft fee means the bank covered it and your balance went negative.
- If your bank refuses, you can escalate. The bank must respond in writing within 56 days, and you can take an unresolved complaint to its external complaints body.
- Prevention beats refunds. Low-balance alerts, a small buffer, and tracking your pre-authorized payments stop almost every NSF fee before it starts.
What Is an NSF Fee?
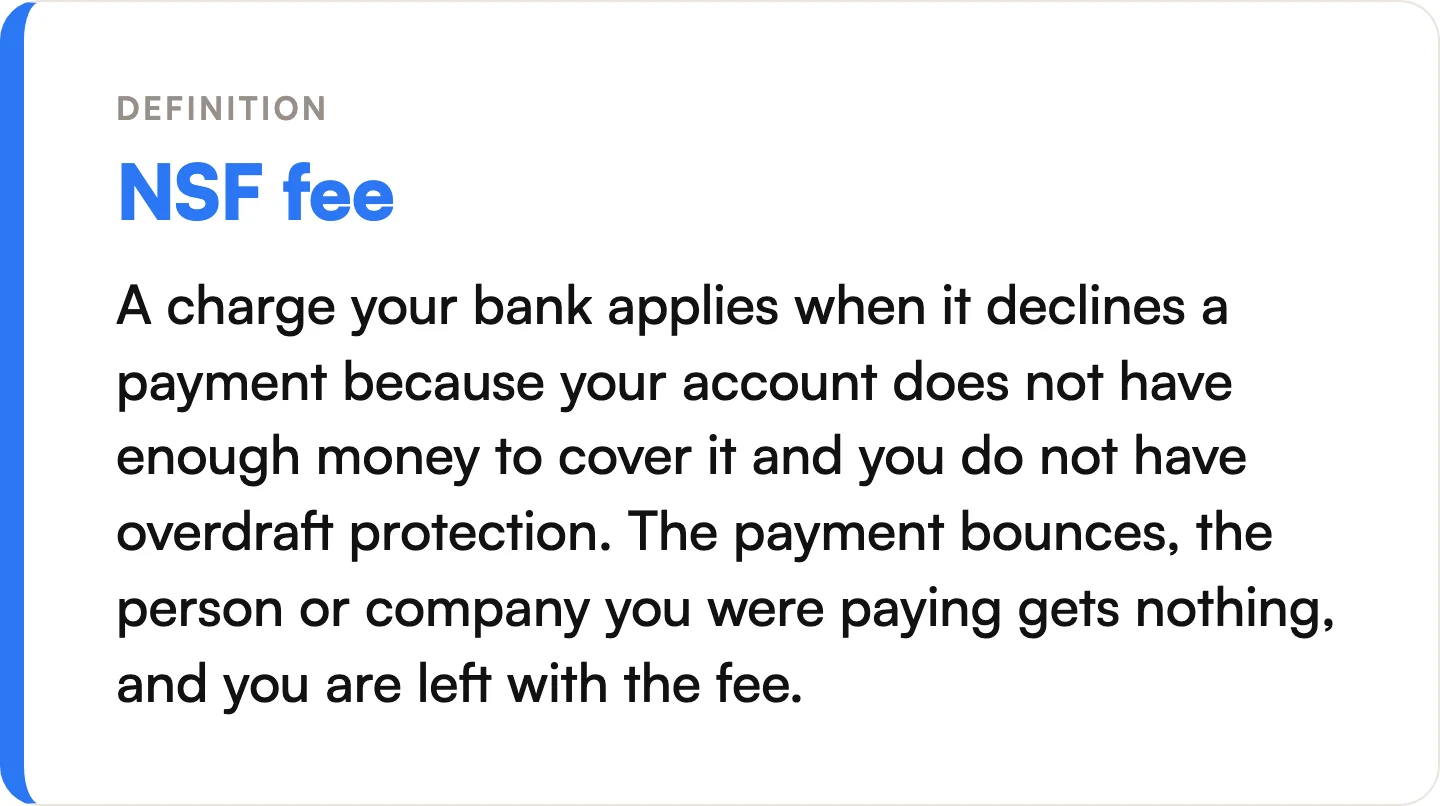
An NSF fee, or non-sufficient funds fee, is a charge your bank applies when it declines a payment because your account does not have enough money to cover it and you do not have overdraft protection. The payment bounces, the person or company you were paying gets nothing, and you are left with the fee.
Common triggers include:
- A pre-authorized debit, such as a rent or insurance payment, that pulls more than your balance
- A cheque that clears when the funds are not there
- A bill payment or e-transfer that exceeds your available balance
- A recurring subscription that charges on a day your account runs low
Because the payment fails, you usually face a second cost too. The company you were paying may add its own returned-payment or late fee, which the Financial Consumer Agency of Canada notes typically runs $20 to $40. So a single bounced payment can cost you on both ends.
NSF Fee vs. Overdraft Fee: What's the Difference?
An NSF fee and an overdraft fee are often confused, but they are opposites. The difference comes down to one thing: whether the bank lets the payment go through.
In short, an NSF fee is a penalty for a payment that did not happen. An overdraft fee is the price of one that did. The new $10 cap below applies to NSF fees specifically, not to overdraft interest.
The New $10 NSF Fee Cap in Canada (2026)
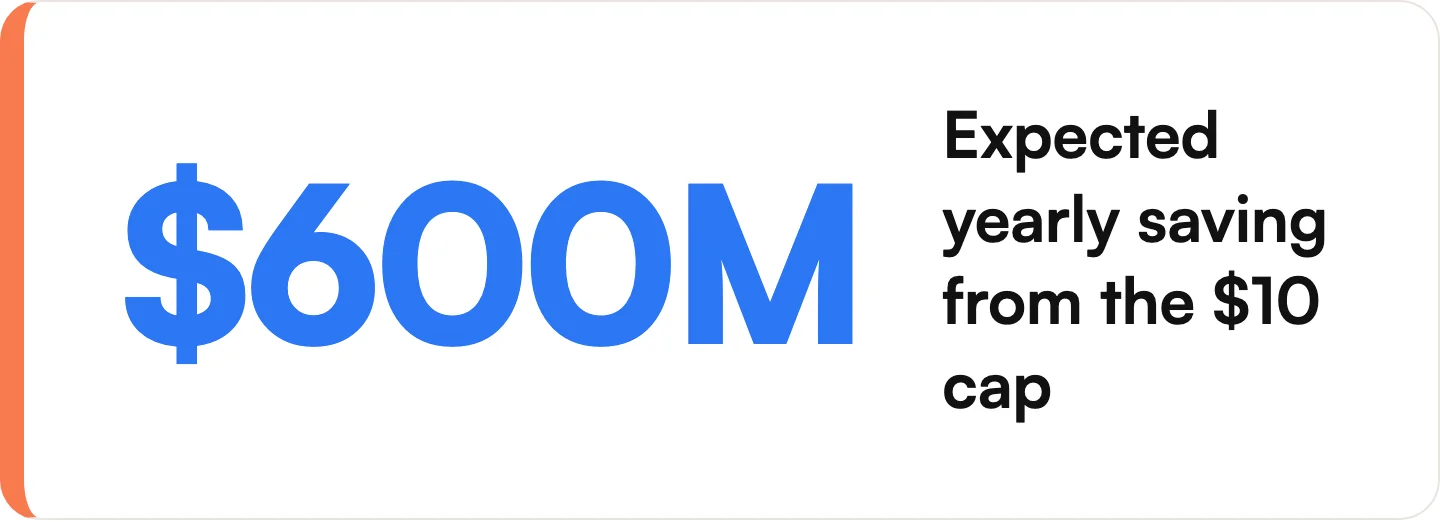
Federally regulated banks in Canada cannot charge more than $10 for an NSF fee. The cap came into force on March 12, 2026, under the Financial Consumer Protection Framework Regulations, and the Department of Finance says it is expected to save Canadians more than $600 million a year.
The regulation does three things, in the words of the Financial Consumer Agency of Canada:
- A hard $10 cap. Banks cannot charge more than $10 for a single NSF fee on a personal deposit account.
- No repeat fees. You cannot be charged an NSF fee more than once within two business days on the same account.
- A small-shortfall exemption. You cannot be charged an NSF fee when your account is short by less than $10.
The rules apply to federally regulated banks and federal credit unions, which includes Canada's largest banks. Before the cap, NSF fees were among the most expensive everyday charges in Canadian banking. The Agency estimates they exceeded $1 billion in charges in 2025, with more than one in three Canadians hit by one each year. The cap does not erase a fee you have already been charged, which is why knowing how to ask for a refund still matters.
How to Get an NSF Fee Refunded: Step by Step
Getting an NSF fee reversed is mostly about how and when you ask. Front-line staff often have the authority to refund a fee as a goodwill gesture, especially for a reliable customer. Follow these steps in order.
- Act fast. Call or message your bank the day you notice the charge. A fresh, first-time request is far easier to approve than one about a fee from weeks ago.
- Gather the facts first. Write down the date of the fee, the amount, and the payment that triggered it. Have any proof handy, such as a payroll schedule or a deposit that landed a day late.
- Use a channel that leaves a record. Phone, in-app secure message, or a branch visit all work. A written record helps if you need to escalate later.
- Keep it short and factual. State the fee, the date, and the reason in a sentence or two. A simple script works well: "I was charged a $10 NSF fee on June 3. My pay deposited one day later than usual. I'd like to request a one-time courtesy reversal."
- Mention your history and ask for a specific outcome. Note how long you have banked there and that this is a rare event, then ask directly for a goodwill reversal of the fee. If several related fees stacked up, ask for all of them.
- Get the outcome in writing. If the fee is reversed, ask for a confirmation number or a secure-message note so you have a record.
It will not work every time. A refund is a courtesy, not a right, and repeated requests are far less likely to land. But a two-minute call to save a fee is almost always worth it.
What to Do If Your Bank Refuses
If the first person says no, you still have a path. Start by escalating inside the bank, then move to an outside complaints body if needed.
- Ask to escalate internally. Politely request a supervisor or the branch manager. Each bank also has a formal complaint process, and you can ask for it by name.
- Know the response deadline. Once you file a formal complaint, the bank must give you a detailed written response within 56 calendar days.
- Take it to the external complaints body. If 56 days pass without resolution, or the bank closes your file and you are not satisfied, you can bring the complaint to the bank's external complaints body, an independent ombudsman.
- Report a rule breach to the regulator. The Financial Consumer Agency of Canada does not settle individual refunds, but it supervises the banks. If you are charged more than the $10 cap allows, you can tell the Agency so it can act on the breach.
NSF Fees by Canadian Bank (Now Capped at $10)
Every federally regulated bank now charges a maximum of $10 for an NSF fee. Here is what the major Canadian banks charged before the cap, based on their published rates, next to the current $10 ceiling.

The takeaway is simple. No matter which of these banks you use, a single NSF fee can no longer cost more than $10, and the repeat-fee and small-shortfall rules apply everywhere. If you want the full picture of what these fees have cost Canadians over time, our NSF fee statistics breakdown has the data.
How to Avoid NSF Fees
Avoiding NSF fees entirely is easier than chasing refunds. A few habits remove almost all of the risk.
- Turn on low-balance alerts. Banks must send you an electronic alert when your balance drops below $100 by default, and you can usually set your own threshold higher. Treat the alert as a cue to move money or pause spending.
- Keep a small buffer. Leaving even $50 to $100 untouched in your chequing account absorbs the small timing gaps that cause most bounced payments.
- Map your pre-authorized payments. List every recurring charge and the day it hits: rent, insurance, phone, subscriptions. Line them up against your pay dates so nothing lands on an empty account.
- Consider overdraft protection, and know its cost. Overdraft protection lets a payment clear instead of bouncing, but it carries its own fee or interest. Our guide to overdraft protection explains when it is worth it and when it is not.
- Choose a low-fee or no-fee account. Many online banks and fintechs do not charge NSF fees at all; they simply decline the transaction. If you bounce payments often, an account built to avoid these fees can pay for itself.
A Better Alternative to Overdraft and NSF Fees: Bree
An NSF fee charges you for not having money, and an overdraft charges you to borrow it on the bank's terms. There is a simpler way to cover a short gap between paycheques.
We're Bree, an interest-free line of credit up to $750 for Canadians who need to bridge a gap before payday, with no credit check, no interest, and no late fees. Where an NSF fee leaves you with a bounced payment and a charge, a Bree line of credit gives you the funds to cover the bill in the first place.
How Bree compares to bank fees:
A few things worth knowing:
- It is free to use. There are no mandatory fees. We make money from optional tips, and funding is free by standard direct deposit in 1 to 3 business days, or within minutes with an optional Express fee.
- No credit check. Approval is based on your bank account history, not your credit score, so a thin or bruised credit file is not a barrier.
- Government benefits count. We accept income from EI, CPP, CCB, and ODSP, which many lenders reject.
- Trusted by Canadians. More than 600,000 people use Bree, and we hold a 4.8 out of 5 rating on Trustpilot.

You can see the full terms on our FAQ page, or get up to $750 with Bree and skip the overdraft math altogether.
Frequently Asked Questions
Can I get an NSF fee refunded?
Often, yes. Banks are not required to refund NSF fees, but they frequently will as a one-time courtesy, especially for a customer in good standing with a first-time or occasional charge. Call or message the bank quickly, explain what happened in a sentence or two, and ask for a goodwill reversal.
How many times will a bank waive NSF fees?
Most banks will consider a courtesy reversal once or twice a year for an established customer. Frequent requests are far more likely to be declined, so it is worth saving your ask for when you genuinely need it rather than every small charge.
How many NSF fees can a bank charge in Canada?
Federally regulated banks cannot charge an NSF fee more than once within two business days on the same personal deposit account. They also cannot charge one at all when your account is short by less than $10, and no single fee can exceed $10.
Are NSF fees legal in Canada?
Yes, NSF fees are legal, but they are now regulated. Since March 12, 2026, the Financial Consumer Protection Framework Regulations cap them at $10 at federally regulated banks and limit how often they can be applied.
What bank has no NSF fees?
Many online banks and fintechs do not charge NSF fees at all; instead of bouncing a payment and charging you, they simply decline the transaction. Among the big traditional banks, there is no longer a meaningful gap, because all federally regulated banks are now capped at $10.
What happens if you don't pay an NSF fee?
The bank adds the fee to your account balance, and you still owe the original payment that bounced, which the company may re-attempt along with its own returned-payment charge. Leaving a chequing account in a negative balance for a long time can lead the bank to restrict or close the account, so it is best to clear it promptly.
The Bottom Line
Getting an NSF fee refunded comes down to asking quickly, politely, and with the facts in hand, and the new $10 cap means a fee that does slip through costs far less than it used to. Still, the best outcome is never being charged at all, which a few alerts and a small buffer will handle for most people.
When the gap between a bill and your next paycheque is the real problem, a fee waiver only treats the symptom. Bree is an interest-free line of credit up to $750 for Canadians, with no credit check and 0% interest, built to cover that gap so a bounced payment never happens. Get started with Bree and leave the overdraft and NSF fees behind.
Sources
- Financial Consumer Agency of Canada: New NSF fee regulations bring down the cost of banking for Canadians
- Department of Finance Canada: Minister Champagne announces new $10 cap on NSF fees
- Canada Gazette: Regulations Amending the Financial Consumer Protection Framework Regulations
- Financial Consumer Agency of Canada: Non-sufficient funds (NSF) fees
- Financial Consumer Agency of Canada: Make a complaint to your financial institution
- Financial Consumer Agency of Canada: Overdraft protection
- Ratehub: Chequing account NSF fees

Join our newsletter to get the latest updates