
E-transfer payday loans in Canada are short-term loans, usually $100 to $1,500, that you apply for online at any hour and receive by Interac e-Transfer, repaid by your next payday within 14 to 62 days. The application really is available 24 hours a day, seven days a week. Whether the money actually lands at 2 a.m. on a Sunday is a different question, and the honest answer is that it depends on whether the lender's approval and payout are fully automated or wait for the next business day.
That gap between "apply 24/7" and "funded 24/7" is where most people get caught out, so this guide focuses on it. We built Bree to give Canadians a cheaper way to cover a gap between paycheques, which means we spend a lot of time explaining how these loans actually work before someone commits to a fee of $14 per $100. Below is what "24/7" really means, what these loans cost, the provincial rules, and the interest-free options worth checking first.
Key Takeaways
- "24/7" describes the application, not always the funding. You can apply any hour, but the money only arrives any hour when the lender's decision and payout are fully automated. Manual review and next-business-day batches push a weekend request to Monday.
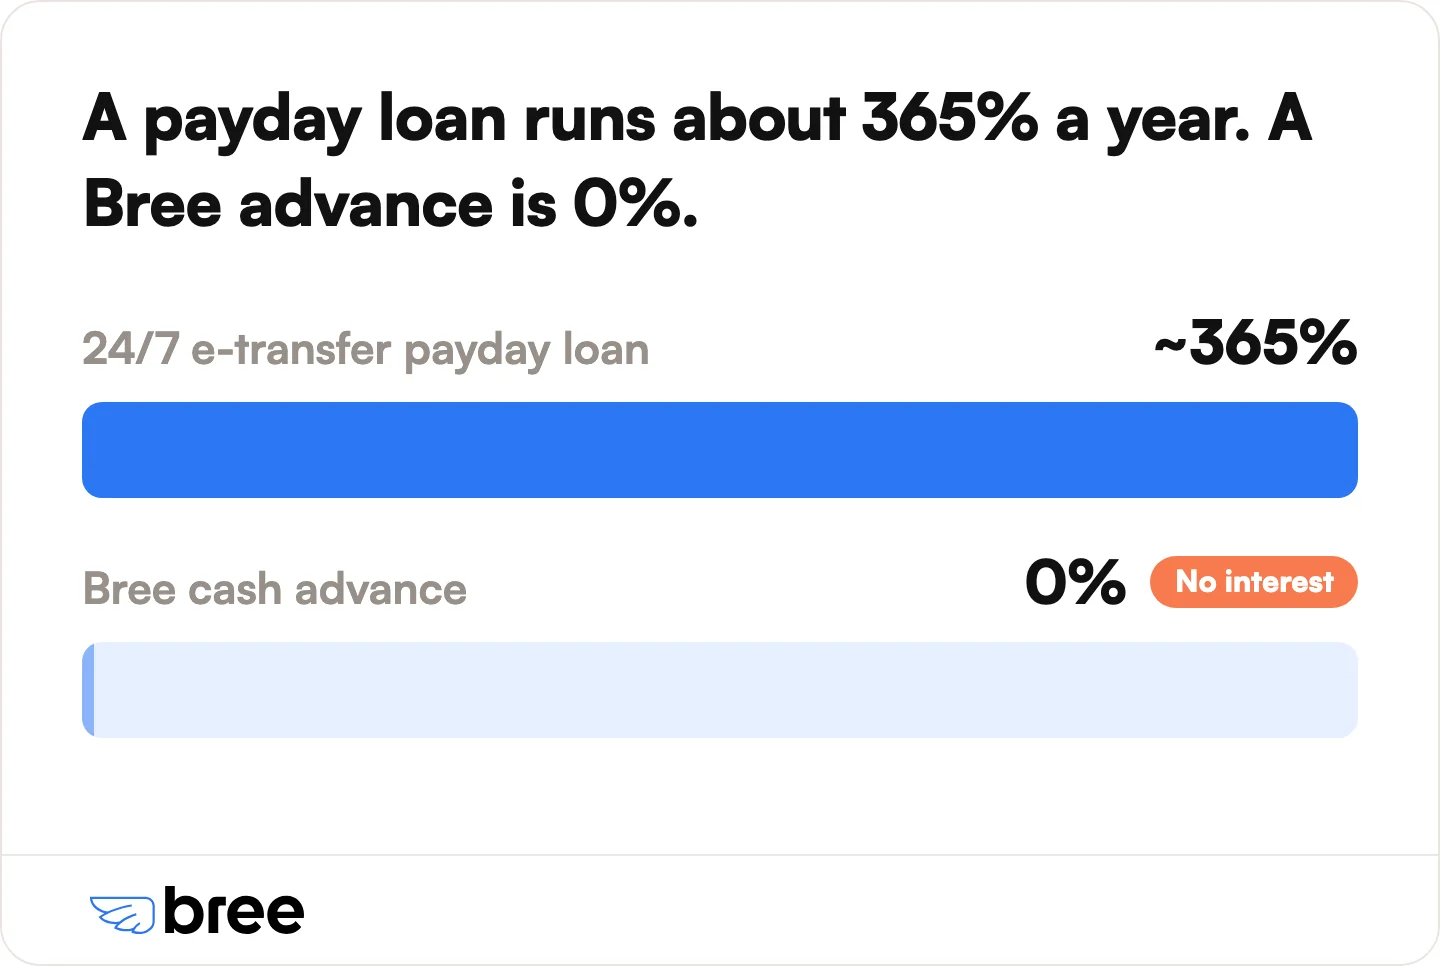
- You pay $14 for every $100, whatever hour you borrow. That federal maximum has held since January 1, 2025, and on a two-week loan it works out to roughly 365% APR.
- Interac e-Transfer itself runs around the clock. Once a lender sends the money, e-Transfer with Autodeposit lands in minutes at any hour. The delay, when there is one, sits with the lender, not the rail.
- Ignore "no refusal" and "guaranteed approval" promises. No licensed Canadian lender can legally approve everyone, so that wording flags an unlicensed or overpriced operator, not a better deal.
- A 0% line of credit is the cheaper way to cover the gap. Bree offers up to $750 in funds at 0% APR, with no credit check and no mandatory fees, sent by direct deposit to your bank account.
What Are E-Transfer Payday Loans?
E-transfer payday loans are small, short-term loans, usually $100 to $1,500, sent to your bank account by Interac e-Transfer and meant to be repaid by your next payday, typically within 14 to 62 days. They are marketed on speed and access: apply online, get a decision in minutes, and skip the paperwork a bank would ask for.
Rather than asking for pay stubs, most lenders verify income by having you link your online banking through a secure, read-only connection. They scan your recent deposits to gauge whether you can repay, and your login password is never kept. If you want the deep dive on the fastest, paperwork-free versions, our guide to the fastest e-transfer payday loans in Canada covers that angle.
Interac is the pipe, not the lender. Interac e-Transfer only carries the money to your account. Everything that makes a payday loan expensive, the fee, the short term, the collection rules, comes from the lender, not from Interac or your bank. A quick transfer tells you nothing about whether the loan behind it is fair.
Are E-Transfer Payday Loans Really Available 24/7?
The application is genuinely available 24/7, but the funding often is not. A service can accept your form at midnight and still not move any money until the next business morning. The test for a truly around-the-clock loan is simple: is the entire chain, both the approval decision and the payout, automated with no human in the loop? If any step waits for a person, it is not really 24/7.
Here is what usually sits behind the "instant, any time" marketing:
- Automated approval vs. a manual review queue. Fully automated systems decide in minutes at any hour. Applications flagged for manual review sit in a queue until staff are back at their desks, so an 11 p.m. Friday "approval" can really mean Monday.
- Instant payout vs. a next-business-day batch. Some lenders collect applications overnight and release funds in a single morning batch. You get a fast decision, but the transfer does not leave until the next business day.
- e-Transfer vs. slower EFT. A few lenders use overnight electronic funds transfer (EFT) and still call it "e-Transfer." EFT can take one to three business days to clear, not minutes.
- Weekends and statutory holidays. Many lenders only process Monday to Friday. A Saturday, Sunday, or holiday application can sit untouched until the next business day even when the website says "open 24/7."

When does the money actually land at night or on a weekend?
Once a lender actually sends the transfer, Interac e-Transfer with Autodeposit lands in your account within minutes at any hour, including nights, weekends, and holidays, because the Interac rail runs around the clock. If you do not have Autodeposit turned on, you have to open the email or text and accept the transfer manually before it deposits, which adds a step but not days.
So the real bottleneck is rarely Interac or your bank. It is whether the lender approved and released your money automatically or parked it in a manual or batch process. When you see "24/7," confirm that both the decision and the payout are automated, or you may be waiting until Monday for cash you thought was coming Friday night.
How Much Do E-Transfer Payday Loans Cost in Canada?
E-transfer payday loans cost $14 for every $100 you borrow. This is the maximum a licensed payday lender can charge under federal rules that took effect on January 1, 2025, and it applies in every province with an approved payday-lending regime, according to the Financial Consumer Agency of Canada. On a standard 14-day loan, that fee works out to an annual interest rate of roughly 365%.
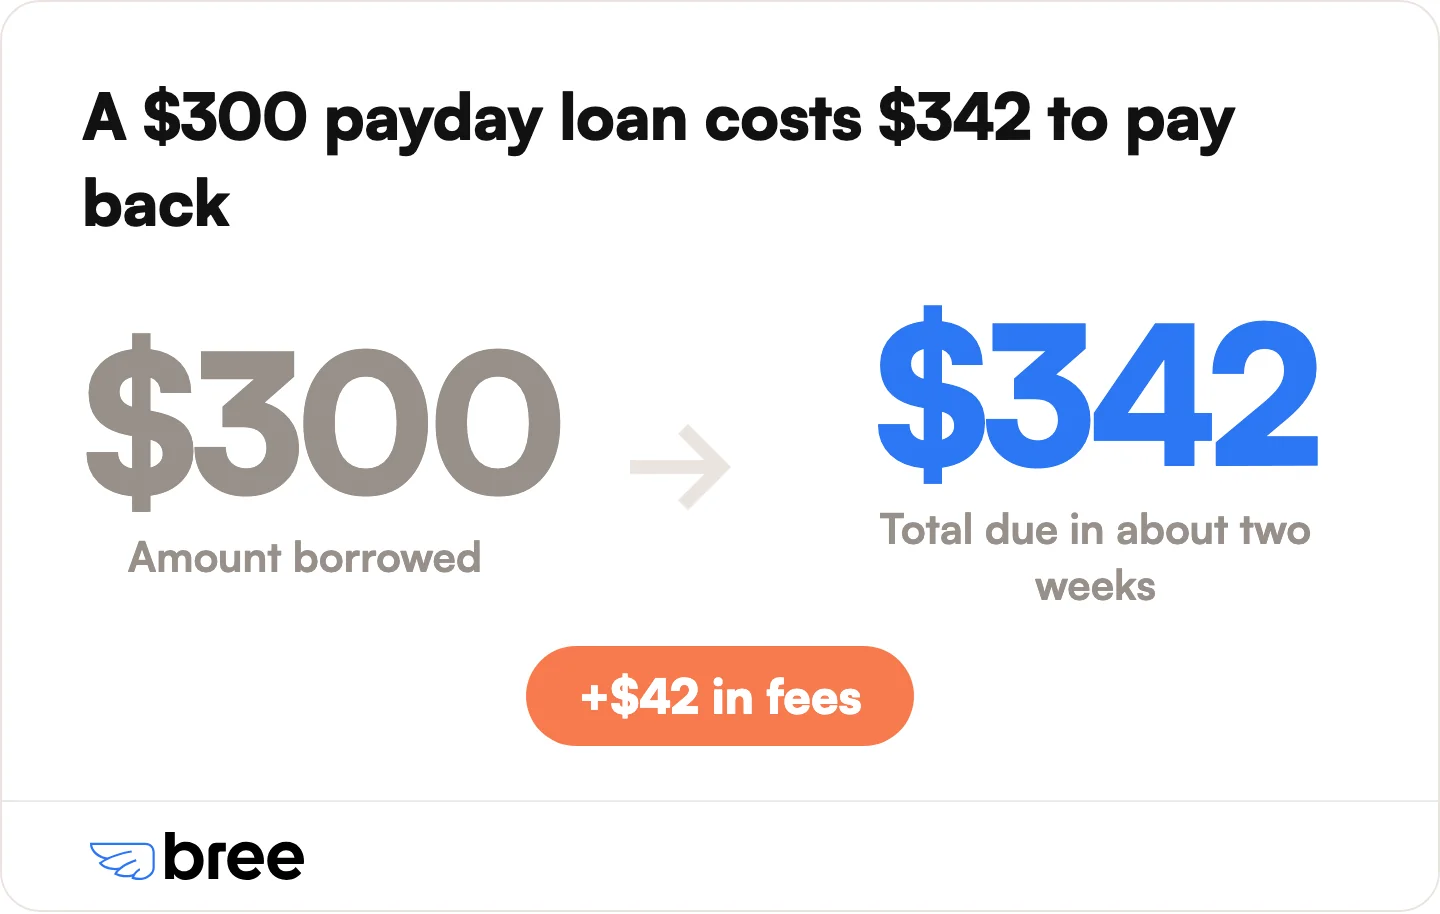
Here is what a $300 loan looks like:
- Amount borrowed: $300
- Borrowing fee: $42 (at $14 per $100)
- Total due in about two weeks: $342
A missed payment adds two more charges on top of that:
- Lender dishonoured-payment fee: if your pre-authorized repayment bounces, the lender can charge a one-time fee of up to $20.
- Bank NSF fee: your bank can add its own non-sufficient-funds fee. Since March 12, 2026, that fee is capped at $10 at federally regulated banks, down from the $45 to $48 it used to run, per the Department of Finance Canada.
Why is the price this high? Even after Canada cut its criminal interest rate from an effective 48% to 35% APR on January 1, 2025, licensed payday loans were carved out of that ceiling, as long as they stay at or below $14 per $100 and follow provincial rules, as MoneySense explained when the rules landed.
Who Qualifies for a 24/7 E-Transfer Payday Loan?
The bar to qualify is low next to a bank loan. Lenders usually ask for:
- Age: at least 18, or the age of majority where you live.
- Residency: Canadian citizen or permanent resident.
- Income: steady deposits, commonly $800 to $1,200 a month or more.
- Banking: an active Canadian chequing account you can log into online.
- Contact: a working email address and phone number.
None of this hinges on a strong credit score. Many lenders run only a soft check to confirm your identity, and some run no credit check at all, which is how these loans reach people the banks turn down.
Benefit income usually counts too. Steady deposits from Employment Insurance, the Canada Pension Plan, Old Age Security, or the Canada Child Benefit are generally treated as qualifying income. We go deeper on the benefit angle for ODSP recipients, for people on social assistance, and for Ontario Works recipients. When your income is a benefit, a lender that accepts it without a credit check matters more than shaving minutes off funding.
What Are the Risks of E-Transfer Payday Loans?
The risk in an e-transfer payday loan is baked into the price and the calendar: the fee is high and the payback date is close. The main dangers:
The cost is the point. A $14-per-$100 fee on a 14-day loan lands near 365% a year. Take $500 and you hand back $570, with $70 of it being pure fee, money that could have covered groceries or a bill.
One loan quietly becomes two. The term is short and the fee is fixed, so a borrower who clears the $70 fee but comes up short again just borrows another $500. Do that twice and the same $500 has now cost $140. The Credit Counselling Society calls this loop the biggest harm payday lending does.
A bounced payment stacks fees. Miss the pre-authorized debit and you can face the lender's dishonoured-payment fee of up to $20 plus your bank's NSF fee, capped at $10 at federally regulated banks since March 12, 2026. It is extra cost piled onto a loan that was already expensive.
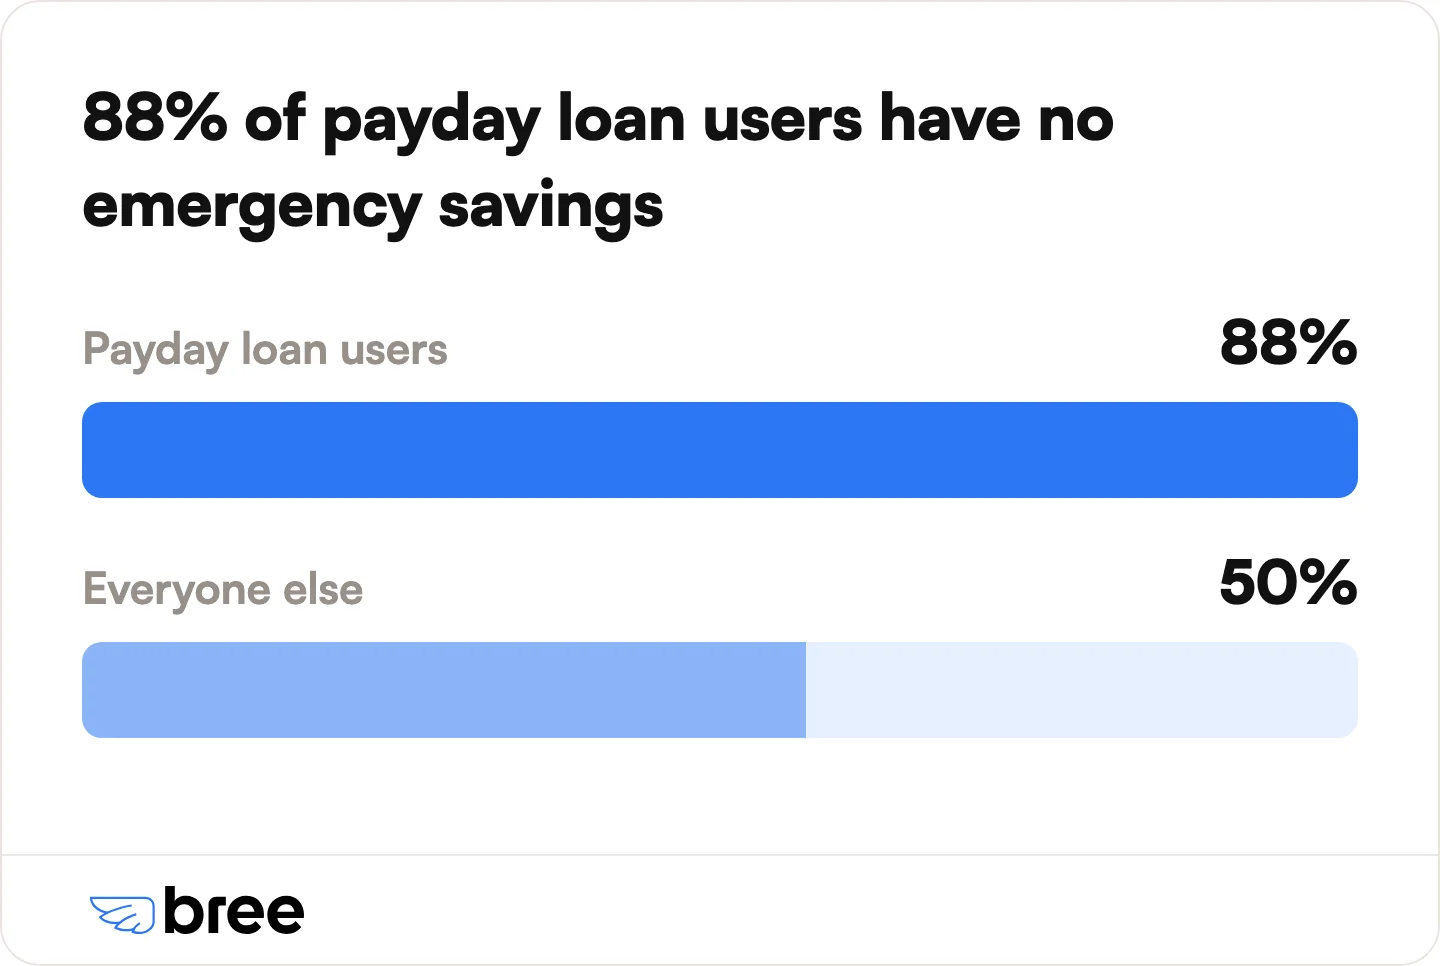
It tracks with thinner finances. Research from the Financial Consumer Agency of Canada links payday borrowing to lower financial wellbeing: 88% of payday users report having no emergency savings, against 50% of everyone else. Fast cash can paper over a budget hole that one loan will not fill.
Are "No Refusal" or "Guaranteed Approval" 24/7 Loans Real?
No. No licensed lender in Canada can legally guarantee approval for everyone, and "no refusal payday loans" is a marketing phrase, not a real product. Every legitimate lender has to assess whether you can repay, which is exactly why they run instant bank verification in the first place.
Read "guaranteed approval," "everyone approved," or "no refusal" as a caution flag, not a selling point. Operators that lead with those words are frequently unlicensed, priced above the legal cap, or hiding fees that only surface after you sign. Genuinely accessible means no credit check and a wider range of accepted income, benefits included, not a pretend promise that nobody gets turned down. Our guide to safer alternatives to no-refusal payday loans covers what to use instead.
Payday Loan Rules by Province
Payday lending is set province by province, even though the federal $14-per-$100 ceiling now applies wherever licensed payday loans exist. The rules that vary most:
Ontario. Lenders can charge no more than $14 per $100, and you get a two-business-day window to cancel a loan for free. After three loans in 63 days you can request an extended payment plan, rollover loans are banned, and every licensed lender has to show its licence number, per the Government of Ontario.
British Columbia. On top of the $14-per-$100 cap, a single loan cannot top 50% of your net pay. The ceiling is $1,500, the term maxes out at 62 days, and a lender cannot roll a loan over or hold more than one of yours at once, according to Consumer Protection BC.
Nova Scotia. The province walked its cap down over several years, from $19 to $17, then $15, reaching $14 per $100 by January 1, 2025. The Province of Nova Scotia also holds the default fee to $20 and requires every fee and term to be disclosed up front.
Quebec and the territories. Quebec's effective 35% APR ceiling leaves no workable margin for payday lenders, so licensed e-transfer payday loans are not offered there. Yukon, the Northwest Territories, and Nunavut run no payday-specific regime, which keeps lenders under the federal 35% criminal-interest limit. We break down the Quebec picture on its own page.
Cash Advance Apps vs. 24/7 E-Transfer Payday Loans
Cash advance apps chase the same moment a payday loan does, cash before payday with no credit check, but at a sliver of the cost. The gap is the fee. A payday lender takes $14 per $100. A line of credit like Bree takes 0% and no mandatory fees, so what you repay is exactly what you borrowed.
The catch is the ceiling. Payday lenders will front up to $1,500, and an app caps lower. For most short gaps between paycheques, a smaller advance at 0% beats a bigger one at $14 per $100. And be clear-eyed about speed: a payday e-transfer can arrive in minutes, our optional Express delivery can too, but our free standard delivery runs 1 to 3 business days. What a cash advance app wins on is price, not racing a lender to the minute.
A Cheaper Alternative: How Bree Works
Bree is a Canadian line of credit used by more than 600,000 people, built to cover a short gap between paycheques at 0% APR. There is no interest and no mandatory fee. We earn from optional tips instead of a $14-per-$100 charge, so the amount you repay is exactly the amount you took.
Every request reaches you the same way: direct deposit to your bank account. Free standard delivery lands in 1 to 3 business days, and optional Express delivery arrives within minutes for a fee. Qualifying takes consistent monthly deposits of at least $1,200, which can include government benefits, plus an active Canadian bank account. There is no credit check of any kind, so the decision rests on your recent banking activity, not a credit score.
You can read the full terms on our instant cash advance page or browse real customer reviews first. If you were about to reach for a payday loan just to get cash before payday, it is worth a minute to see whether a 0% line of credit covers the gap instead.
How to Borrow Responsibly (If You Still Use One)
If an e-transfer payday loan is still your best option, a few habits limit the damage:
Borrow only what you can repay in full. Check that your next paycheque will cover the loan plus the fee and still leave you enough to live on. If it will not, the loan will likely turn into two.
Confirm the lender is licensed. Check your provincial consumer-protection office for the lender's licence. Unlicensed lenders may charge above the legal cap, use aggressive collection tactics, or offer no consumer protection at all.
Read the agreement before you sign. Confirm the total you are borrowing, every fee the lender charges, the repayment date and method, and the penalty for a missed payment.
Set repayment up to succeed. Most lenders pull repayment by pre-authorized debit. Make sure the money is there on the date, because a bounced payment triggers a dishonoured-payment fee of up to $20 and a bank NSF fee of up to $10 at a federally regulated bank.
Do not stack loans. Taking a new payday loan to pay off an old one is how the debt cycle starts, and most provinces prohibit holding more than one payday loan at a time.
Frequently Asked Questions
Is there a truly 24/7 e-transfer payday loan in Canada?
Some lenders are genuinely 24/7 and some only look it. A truly around-the-clock loan automates both the approval decision and the payout, so money can land at any hour. Many services accept applications 24/7 but process approvals or transfers only during business hours, which means a late-night or weekend request can wait until the next business day. Before you rely on one, confirm that both the decision and the funding are automated.
Can I get an e-transfer payday loan on a weekend or holiday?
Sometimes. If the lender fully automates approval and payout, an Interac e-Transfer can arrive within minutes on a Saturday, Sunday, or statutory holiday. If any step needs a person, or the lender releases funds in a next-business-day batch, your money may not move until the next business day even though you applied on the weekend.
How fast does the money actually arrive?
Once a lender sends the transfer, Interac e-Transfer with Autodeposit lands in your account within minutes at any hour. The variable is the lender, not the rail. A fully automated lender can fund in minutes, while one that uses manual review, a morning batch, or slower EFT can take hours or one to three business days.
How do I repay an e-transfer payday loan?
Most lenders pull the full balance plus the fee automatically on your next payday by pre-authorized debit. If the money will not be there in time, reach out to the lender before the debit date to ask about an extension, because a bounced payment triggers the lender's dishonoured-payment fee of up to $20 and your bank's NSF fee on top.
Does a payday loan affect your credit score?
Usually not directly. Most payday lenders do not report on-time payments to the credit bureaus, so repaying one will not build your credit. If you default or miss payments, though, the debt can be sent to collections and reported, which does damage your score. Some lenders also run a soft credit check that does not affect your score.
What is the maximum I can borrow?
Most provinces cap a first payday loan at $1,500, and the exact amount a lender offers depends on your income and existing obligations. British Columbia adds a rule that a single loan cannot exceed 50% of your net pay. A cash advance app like Bree caps lower, at up to $750, but at 0% interest instead of $14 per $100.
What is the difference between a 24/7 e-transfer loan and a cash advance app?
A 24/7 e-transfer payday loan is a licensed short-term loan priced at $14 per $100, near 365% APR, delivered by Interac e-Transfer. Bree's line of credit offers up to $750 at 0% APR with no credit check and no mandatory fees, paid by direct deposit to your bank account. A payday lender can hand you more, but a cash advance app is far cheaper for the same job of covering a gap before payday.
Conclusion
Treat "24/7" as a question, not a guarantee. The application really is open at any hour, but the cash only shows up at any hour when the lender has automated both the yes and the payout. The Interac rail itself never sleeps, so a late transfer is almost always the lender stalling, not the network. None of that changes the price either: at $14 per $100, roughly 365% APR, these are among the costliest ways to borrow, with a payback window short enough to pull people back for a second loan.
It is worth pricing the alternative before you commit. Bree is a Canadian line of credit that helps more than 600,000 people cover the space between paycheques at 0% APR: up to $750, no credit check, no mandatory fees, and direct deposit straight to a bank account. When the real goal is simply cash before payday, an interest-free line of credit often does the job. You can get started with Bree in a few minutes.
Sources
- Financial Consumer Agency of Canada: Payday loans
- Financial Consumer Agency of Canada: Understanding payday loan use in Canada
- Department of Finance Canada: New $10 cap on NSF fees
- MoneySense: Canada's new rules for high-interest payday loans
- Government of Ontario: Payday loans, your rights
- Consumer Protection BC: Payday loans
- Province of Nova Scotia: Payday loans, your rights
- Credit Counselling Society: How to escape the payday loan nightmare

Join our newsletter to get the latest updates


