
Ontario Works pays a single person up to $733 a month, and once rent comes out there is rarely anything left for a car repair or a hydro bill. When that gap hits, payday loans that accept Ontario Works advertise instant approval for anyone on a benefit, at any credit score. They will take you. They will also charge you the most of any option on the shelf.
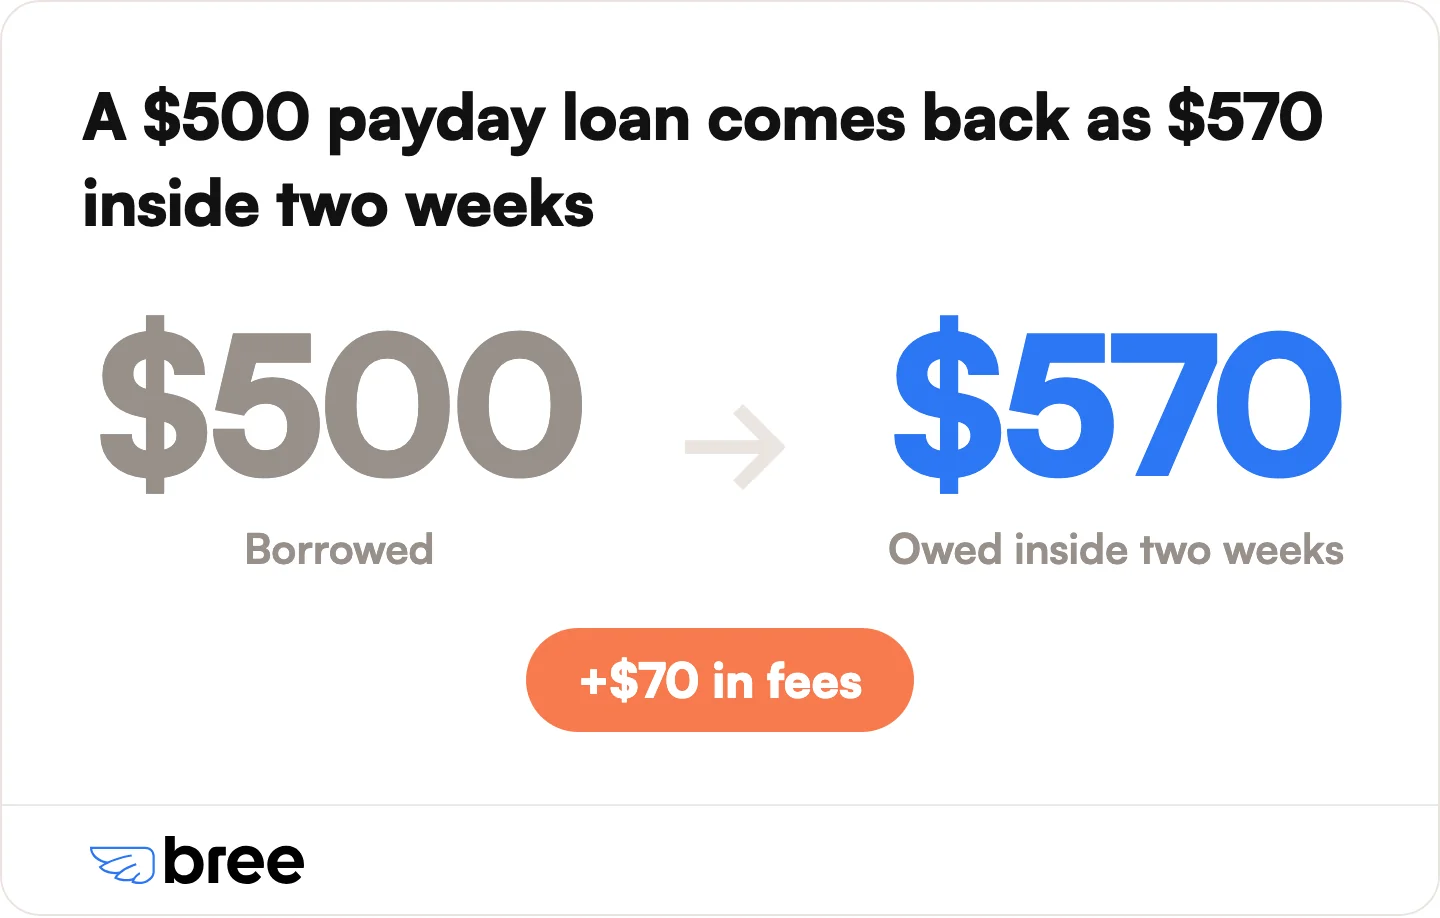
A payday loan in Ontario costs $14 for every $100 you borrow, about 365% a year, so a $500 shortfall turns into $570 owed inside two weeks. There are cheaper ways to borrow on Ontario Works, and there is free help most recipients never hear about. This guide covers who lends to Ontario Works recipients, what each option really costs on a $733 cheque, and how to get emergency money without handing a chunk of your benefit to a lender.
Key Takeaways
- Ontario Works counts as income. Payday lenders and cash advance apps approve you on the government deposits in your bank account, not your credit score, so a low credit score does not shut you out.
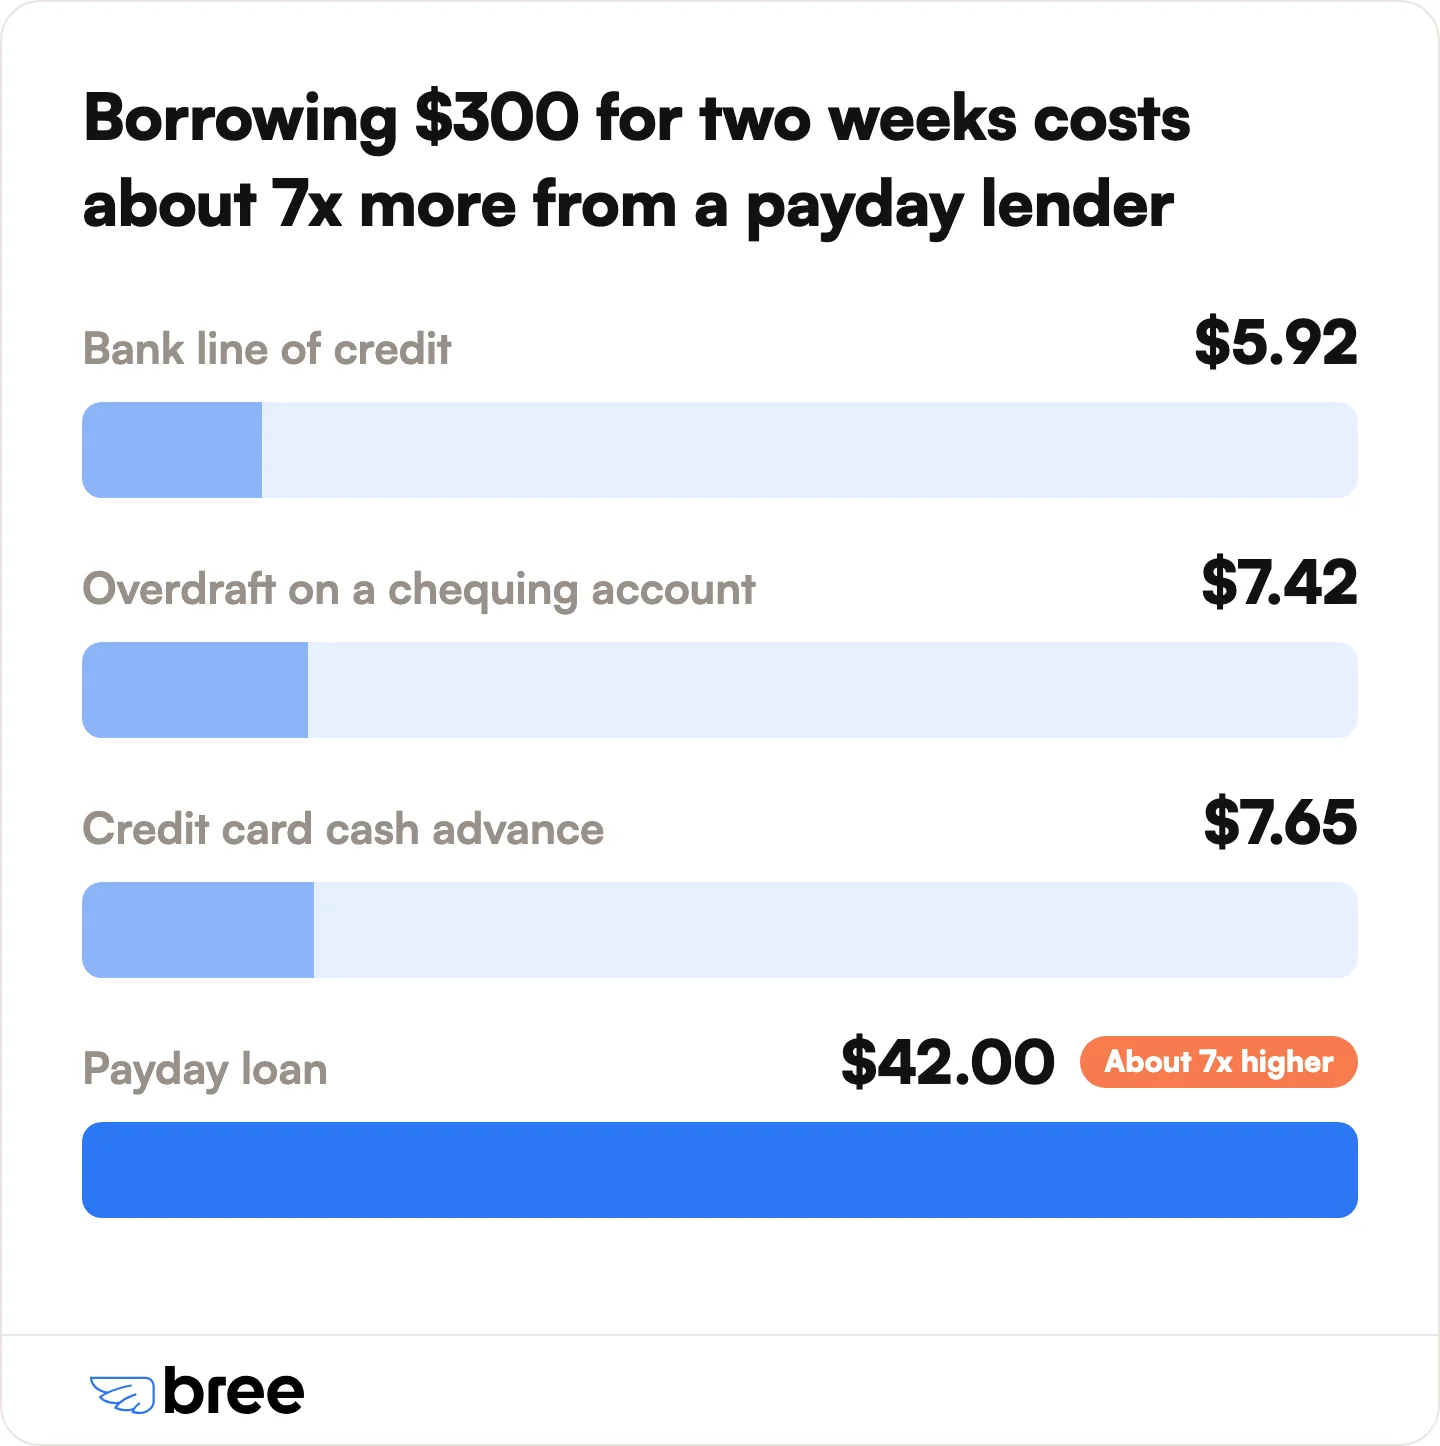
- A payday loan is the most expensive way to borrow. At $14 per $100, about 365% a year, borrowing $300 for two weeks costs $42.00 through a payday lender, versus $5.92 on a bank line of credit (Financial Consumer Agency of Canada).
- Ontario caps a payday loan at 50% of your net income per loan. For a single recipient living on $733 a month, that works out to a real limit of roughly $366, not the $1,500 lenders advertise.
- The cheapest way to borrow is an interest-free line of credit of up to $750, which runs at 0% interest, skips the credit check, and counts Ontario Works as income.
- Bank NSF fees now cap at $10. On a personal account at a federally regulated bank, a non-sufficient-funds charge cannot exceed $10 as of March 12, 2026, down from the $45 to $48 charged before (a payday lender's own dishonoured-payment fee is separate).
- Free help comes first. Ontario Works offers emergency assistance for urgent costs, and 211 Ontario connects you with local support at no charge, before any loan.
Can You Get a Payday Loan on Ontario Works? (2026)
Yes. Ontario Works recipients can get payday loans, cash advance apps and installment loans from lenders that accept government benefits as income. These lenders read the recurring deposits in your bank account instead of running a hard credit check, so Ontario Works, ODSP, CPP, EI and other benefits all count as a reliable source of income (Government of Ontario).
Ontario Works pays a single person up to $733 a month for basic needs and shelter, deposited on the last business day of the previous month (Government of Ontario). That predictable monthly deposit is exactly what a lender looks for. Approval usually rests on the deposit landing on schedule and on there being enough left after essentials to cover repayment.
Your assets do not block a loan either. Ontario Works limits assets to $10,000 for a single person and $15,000 for a couple, plus $500 for each dependant, but payday lenders and cash advance apps do not check asset levels (Government of Ontario). They confirm income through your bank account and nothing more. Traditional banks are the opposite. They usually reject Ontario Works applications because $733 a month sits far below their minimum income rules, which is what pushes recipients toward high-cost lenders in the first place.
What Payday Loans Really Cost in Ontario
Of every way to cover an Ontario Works shortfall, a payday loan carries the highest price. In Ontario the legal ceiling is $14 for each $100 borrowed, which annualizes to roughly 365% (Financial Consumer Agency of Canada). The most a lender will advance is $1,500, repayable over as many as 62 days.
Put $300 on a payday loan and you hand back $342. Put $500 on one and you hand back $570, a $70 charge that swallows nearly a tenth of a single $733 cheque in two weeks. Storefront or online, the price is identical.
The gap between a payday loan and every cheaper option is stark. The Financial Consumer Agency of Canada puts the cost of borrowing $300 for two weeks side by side:
The same $300 costs about seven times more from a payday lender than on a bank line of credit. On a fixed benefit, that gap is a week of groceries.
Ontario's Payday Loan Rules (and What They Protect)
Ontario's Payday Loans Act sets hard limits on what a lender can charge and do, and knowing them is the difference between using a payday loan carefully and getting trapped by one. These rules apply to every licensed payday lender in the province (Government of Ontario).
- 50% of net income per loan. A lender cannot loan you more than half your net monthly income in a single payday loan. For a single Ontario Works recipient on $733, that caps a payday loan at roughly $366, well below the $1,500 maximum lenders advertise.
- $14 per $100 maximum cost. Ontario limits the cost of a payday loan to $14 for every $100 borrowed, which works out to about 365% a year.
- $20 cap on dishonoured payment fees. If your payment bounces, a payday lender can charge you no more than $20 on top of any fee from your bank.
- Two business days to cancel. You can cancel a payday loan within two business days without any penalty or reason.
- An extended payment plan after three loans. If you take out three payday loans within 63 days, the lender must offer you an extended payment plan, which lets you repay in instalments instead of one lump sum.
One more rule works in your favour outside the payday world. Since March 12, 2026, banks cannot charge more than $10 for a non-sufficient funds (NSF) event on a personal account, down from the $45 to $48 that was typical before (Financial Consumer Agency of Canada). That matters for Ontario Works recipients, because a bounced payment when your balance runs low used to cost more than the emergency you borrowed for.
Your Options, Ranked From Most to Least Expensive
You have several ways to cover a gap on Ontario Works, and they are not close in price. Here they are ranked from the most expensive to the cheapest, with the cost to borrow $500 as the yardstick.
Payday loans (last resort)
Payday lenders such as Money Mart accept Ontario Works and fund fast, usually by e-transfer, but they are the most expensive option here. At $14 per $100, about 365% a year, a payday loan traps borrowers who cannot repay the full amount plus the fee before the money runs out. On a $733 cheque, that happens fast. Use a payday loan only when nothing cheaper is available.
Installment loans (a cheaper middle ground)
Installment lenders lend larger amounts, into the thousands of dollars, spread over several months at mid-range interest rates, and they accept a range of government income. Cashco Financial is one lender that works this way, with instalment loans rather than a classic $14-per-$100 payday product. These loans cost far less than a payday loan but still carry real interest, so they suit a larger planned expense rather than a small gap before your next benefit.
Cash advance apps and an interest-free line of credit (best value)
Cash advance apps and interest-free lines of credit are the cheapest way to bridge a short gap on Ontario Works. Three of them accept government benefits as income:
- Bree runs to $750 as an interest-free line of credit, at 0% interest, with no credit check and nothing you are required to pay to borrow.
- KOHO Cover offers up to $250 at 0% interest through a paid monthly plan.
- Nyble offers up to $250 at 0% interest, with a free tier and a paid tier for faster funding.
Of the three, an interest-free line of credit covers the largest amount and charges nothing to borrow.
The cheapest option is not a loan at all
Before you borrow anything, Ontario Works can sometimes give you the money for free. Emergency assistance and discretionary benefits are covered in the next section, and for a true one-off cost they beat every loan on this list.
Why Bree Works for Ontario Works Recipients
We built Bree as an interest-free line of credit for Canadians caught between payments, and Ontario Works qualifies as income here. The line tops out at $750, charges 0% interest, and carries no credit check, no late fees and no mandatory fees of any kind. Ontario Works, ODSP, CPP, the Canada Child Benefit and EI all count.
Money moves to your bank account by direct deposit. The free route clears in one to three business days; pay the optional express fee and it arrives within minutes. Repayment runs on your own schedule, and you see your terms before you accept, so nothing is deducted on a date you did not agree to.
Approval is honest, not guaranteed. We look for roughly $1,200 a month in steady deposits over your last two months of banking, so Ontario Works alone at $733 can come up short. Recipients who pair it with ODSP, a part-time job or another benefit have the best shot. Using Bree costs nothing at all. We stay funded through optional tips, closer to tipping a server than paying a fee, which is why there is no interest and no required charge to borrow. On Trustpilot, Bree scores 4.8 out of 5 across more than 8,000 reviews, and its user base has passed 600,000 Canadians. Coverage differs from province to province, so open the app to confirm Bree is available where you live.
See if you qualify for up to $750 with Bree.
What You Need to Qualify for a Loan on Ontario Works
Most lenders that accept Ontario Works keep their requirements simple, because approval rests on your benefit deposits rather than your credit or employment. If your Ontario Works payment lands in the same account on a regular schedule, you meet the main test.
Basic requirements are:
- 18 years or older
- An Ontario resident with a valid address
- A bank account that receives your Ontario Works payment by direct deposit
- Government-issued ID, plus an email and phone number
Lenders accept a range of government income, including Ontario Works, ODSP, CPP, EI and other benefits deposited to your account, and many will add part-time employment income on top. Your asset level does not affect eligibility, since lenders check income, not what you own.
Skipping the credit check is not the same as guaranteed approval. Treat any lender that promises to approve every Ontario Works recipient as a red flag, because a real one still confirms your account sees enough money to cover what you repay. If you are on disability instead of Ontario Works, our guide to payday loans that accept disability in Canada covers what qualifies in that case.
Before You Borrow: Free Help First
Before you take on any loan, check whether you can get the money for free. Several programs help Ontario Works recipients cover an emergency without borrowing at all.
- Ontario Works emergency assistance. If you are facing an urgent situation, such as an eviction or a utility shut-off, Ontario Works can provide emergency financial help even before a full application is processed. Ask your caseworker about emergency assistance and discretionary benefits.
- 211 Ontario. Call 2-1-1 or visit 211ontario.ca to find local emergency funds, food banks, rent help and utility support at no cost.
- Credit unions. A credit union you already bank with may offer a small emergency loan at rates far below a payday lender. It is not free, but it is a much cheaper way to borrow than a payday storefront.
- Credit counselling. A non-profit credit counsellor can help you manage existing debt for free, which often beats borrowing more.
- Family or friends. Borrowing informally from someone you trust skips interest and credit checks altogether, and it keeps the money out of a lender's hands.
For a genuine one-time cost, these options cost nothing and protect next month's cheque. A loan of any kind should come after you have ruled them out.
How to Apply in Minutes
The application itself is short, and it runs the same way whether you pick a payday lender or a cash advance app.
- Price it before you pick it. A 0% line of credit and a 365% payday loan both approve on your Ontario Works deposits, so speed is not the tiebreaker, price is. On a $500 draw, the cheaper option keeps the whole $70 fee in your pocket.
- Enter your details. You give a name, address, email, phone number and your banking information, and most lenders ask for little beyond that.
- Link your bank account. Linking it lets an automated check see your Ontario Works deposits arriving on time. There is no form to fax and no pay stub to dig up.
- Wait for the answer. Decisions usually come back in a few minutes, weighed on your benefit history and how much room your cheque leaves to repay.
- Collect the money. A payday lender typically e-transfers it in 15 to 30 minutes. Bree sends it by direct deposit instead, in minutes with the optional express fee or free within one to three business days.
- Repay on schedule. A payday loan falls due as one lump sum, usually by automatic withdrawal, within 62 days. With Bree, repayment follows your own schedule and the terms are shown before you accept. On any loan, a missed payment can trigger an NSF fee, so map out repayment before you borrow.
You can also check your exact Ontario Works payment dates so you know when money lands and can plan around the gap instead of borrowing through it.
How the Payday Debt Trap Works on $733 a Month
On a fixed Ontario Works income, the trap is arithmetic. Rent in most Ontario cities already claims the biggest slice of a $733 cheque, and food, utilities and transit take much of what is left, so a two-week payday due date arrives with the money mostly spent. Repaying $570 on a $500 loan then means going without something essential.
That is the moment the cycle starts. Short one repayment, a borrower takes a fresh payday loan to clear the old one, pays another fee, and begins the next two weeks further behind. The principal never shrinks; only the fees stack up. A single $500 emergency can cost hundreds of dollars over a few months while the debt itself never clears.
Three moves keep you clear of it. Only borrow what next month's cheque can absorb. Take the 0% route whenever a payday loan and a line of credit both say yes. And refuse to roll one loan into the next. If the shortfall is really about timing, our guide to cheaper ways to borrow while on social assistance lays out the lower-cost routes in more detail.
Frequently Asked Questions
Can Ontario Works recipients get a payday loan with bad credit?
Yes. Payday lenders and cash advance apps approve Ontario Works recipients with bad credit or no credit history, because they verify your government deposits instead of running a hard credit check. Your credit score does not block approval when your Ontario Works payment lands on a regular schedule. The catch is cost, not eligibility, so compare a 0% option before you accept a 365% payday loan.
How much can you borrow on Ontario Works?
Ontario caps a payday loan at 50% of your net income per loan, which for a single recipient on $733 a month is roughly $366, even though lenders advertise up to $1,500. Cash advance apps such as KOHO Cover and Nyble reach $250. An interest-free line of credit like Bree goes up to $750 based on your income. Installment loans go higher, into the thousands, but carry real interest.
Can I get a payday loan online with ODSP in Ontario?
Yes. ODSP counts as verifiable income, so payday lenders and cash advance apps that accept government benefits will approve an online application on ODSP the same way they do on Ontario Works. ODSP pays a single person up to $1,436 a month, which is higher than Ontario Works and clears more lenders' income minimums. You can see when payments land on our ODSP payment dates guide.
What happens if you cannot repay a loan on Ontario Works?
Reach out to your lender the moment you know you will be short. Miss the payment and a payday lender can add a dishonoured-payment fee of up to $20 and refer the debt to collections, while your bank may pile on an NSF fee, now capped at $10 on personal accounts at federally regulated banks. Several failed withdrawals can stack those NSF charges quickly. Bree charges no late fees and works with borrowers who fall behind. And never take out a new payday loan just to cover an old one.
What is the safest way to borrow $500 on Ontario Works?
The safest way to borrow $500 on Ontario Works is the cheapest one that you can repay without missing an essential bill. An interest-free line of credit of up to $750 costs $0 to borrow, against a $70 fee on a $500 payday loan, and both approve on your benefit deposits rather than your credit. Before borrowing at all, ask your Ontario Works caseworker about emergency assistance, which can cover a genuine one-off cost for free.
Can you apply online for a loan on Ontario Works?
Yes. Most payday lenders and cash advance apps let you apply online 24/7 from a phone or computer, and the application takes minutes. You connect your bank account so the lender can confirm your Ontario Works deposits, with no paperwork to fax. Bree's entire process is online, from applying to receiving your funds by direct deposit.
The Bottom Line
A payday loan is rarely the only way to cover an Ontario Works shortfall, and it is almost always the priciest. At $14 per $100 it drains a tenth of a $733 cheque in fees, and Ontario's own 50% rule caps what a single recipient can even borrow at around $366. Start with the free routes first: Ontario Works emergency assistance and 211 Ontario. If you still need to borrow, the zero-interest options take the same government income and cost a fraction of a payday loan.
For anyone bridging the gap on Ontario Works, ODSP, CPP or EI, our interest-free line of credit runs up to $750 at 0% interest, with no credit check, no mandatory fees, and repayment on your own schedule. See if you qualify for up to $750.
Sources
- Government of Ontario: Ontario Works
- Government of Ontario: Financial assistance through Ontario Works
- Government of Ontario: Eligibility for Ontario Works financial assistance
- Government of Ontario: Payday loans, your rights
- Financial Consumer Agency of Canada: Payday loans
- Financial Consumer Agency of Canada: New NSF fee regulations
- Government of Ontario: Ontario Disability Support Program

Join our newsletter to get the latest updates


