
The best KOHO alternative in Canada depends on which part of KOHO you want to replace. If you are after a cash advance to cover a bill before payday, Bree gives you up to $750 at 0% interest with no credit check, well above KOHO Cover's $250 limit. If you want a better everyday account instead, EQ Bank leads on savings, Neo Financial on cashback, Wealthsimple on banking with investing, and Wise on travel and multi-currency spending. This guide covers all seven picks, what each is best for, and what KOHO Cover actually costs.
Key Takeaways
- KOHO does two jobs, so "KOHO alternatives" splits in two. Replace the spending and savings card with EQ Bank, Neo, Wealthsimple, or Wise; replace the KOHO Cover advance with a dedicated cash advance app.
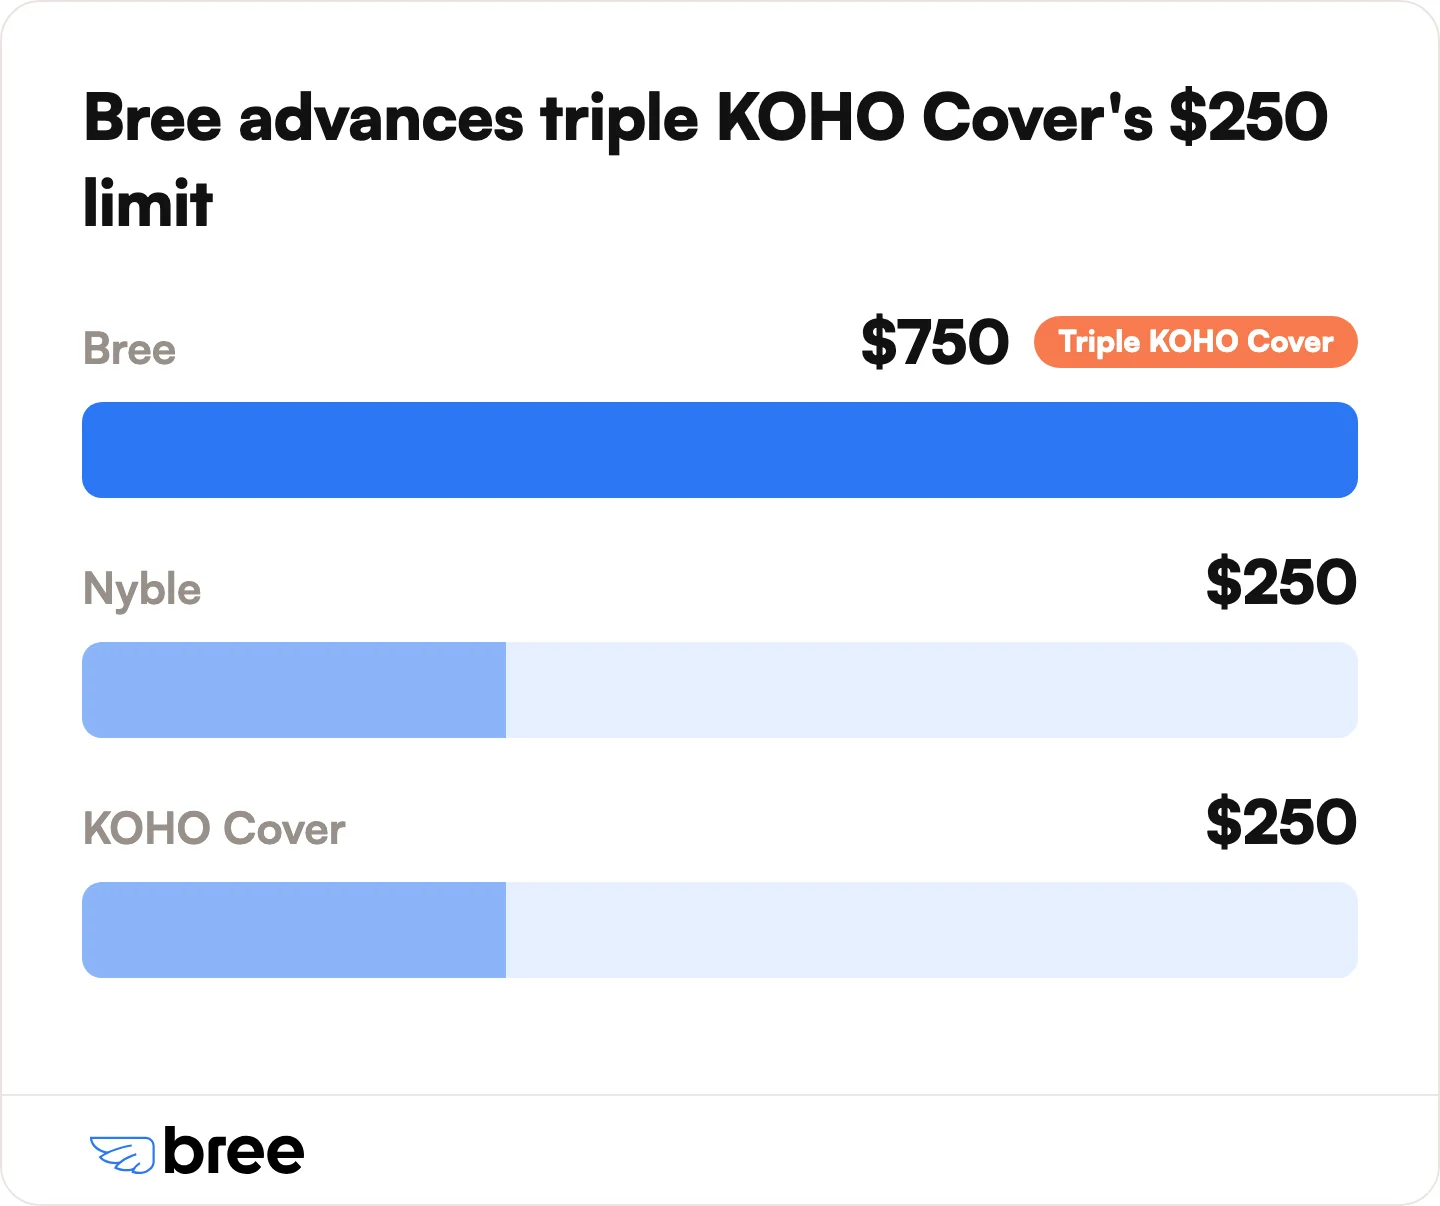
- Bree tops the list for interest-free borrowing at $750, three times KOHO Cover's $250 cap, and it runs no credit check and charges nothing mandatory.
- KOHO Cover is not truly free. The advance itself charges 0% interest, but Cover is a paid monthly subscription, so you carry a recurring fee for the option to borrow even in months you never use it.
- Nyble earns its place on credit reporting, not size. With a $250 ceiling and Equifax reporting, it suits people whose first goal is a better score rather than a bigger advance.
- Skip the payday loan. The federal cap still lets lenders charge $14 per $100, around 365% APR, so even a paid app tier undercuts it and a 0% advance buries it.

7 Best KOHO Alternatives in Canada
KOHO bundles a prepaid card, a savings account, and the KOHO Cover advance into one app, so the right alternative depends on which of those you actually used. Here is how the seven picks compare by job, along with the one thing that matters most to anyone who left over the Cover feature: only the cash advance apps hand you money before payday.
1. Bree: Best for Interest-Free Funds up to $750
Bree is an app we built for Canadians who need more than a $250 top-up before payday. You can request up to $750 at 0% interest, with no credit check and nothing mandatory to pay. The money is a direct deposit into your own bank account, so it is yours to move and spend directly, rather than a balance held inside the KOHO app. Standard funding is free and takes one to three business days; when you need it sooner, an optional express fee brings it within minutes. Repayment then comes off on your own schedule.
Where most KOHO alternatives turn away government income, we count it: ODSP, OW, CPP, EI, and CCB all qualify. The full terms live on our line of credit page.
Pros:
- A $750 ceiling, triple what KOHO Cover offers
- 0% interest with no recurring monthly charge
- Approval runs on your banking history, not a credit pull
- Government benefits count as qualifying income
Not for you if: one advance has to clear more than $750, or a credit-building tool is what you are really after, since Bree deliberately stays off your credit report.
Proof: Bree's Trustpilot reviews sit at 4.8 out of 5 from over 8,000 ratings, and its user base has grown past 600,000 Canadians.
2. Nyble: Best for Building Credit While You Borrow
Nyble pairs a small interest-free line of credit, up to $250, with the thing that sets it apart: it reports your repayments to Equifax to help build your credit. Getting started takes no hard credit check, and the base tier is free, while instant funding and extra perks sit behind an optional paid monthly plan. Because the whole point is your score, a missed payment cuts both ways and can pull that score back down.
For a direct head-to-head on limits, cost, and funding speed, see our Bree vs Nyble comparison.
Pros:
- Reports on-time payments to Equifax to help build credit
- 0% interest on the line of credit
- No hard credit check to start
- Free base tier
Not for you if: you need more than $250, or you want cash without paying a monthly fee for instant funding.
3. EQ Bank: Best for High-Interest Savings

EQ Bank is an online bank for savers who want a higher interest rate than the traditional big banks pay, with no monthly account fee and no minimum balance. It does not offer a cash advance, so it will not help you cover a bill before payday, but if you left KOHO mainly for a better place to hold your money, it is the strongest pick. Tangerine and Simplii Financial compete in the same no-fee everyday-banking space; see our KOHO vs Tangerine comparison for that side of the decision.
4. Neo Financial: Best for Everyday Cashback Rewards
Neo Financial is a Canadian fintech that bundles a spending account, a savings account, and a rewards card with cashback at partner merchants, all with no monthly account fee. It fits if you used KOHO mostly for its prepaid card and cashback rather than the Cover advance. For a closer look at how the two stack up, see our KOHO vs Neo comparison.
5. Wealthsimple: Best for Banking Plus Investing
Wealthsimple combines everyday spending, saving, and investing in one app, which suits people who want their cash account and their investments in the same place. Like the other banking options here, it does not offer a payday advance, so it replaces KOHO's card and account rather than its Cover feature.
6. Wise: Best for Travel and Multi-Currency
Wise is the pick if you travel or send money abroad, because it lets you hold and exchange dozens of currencies at the mid-market rate with no monthly subscription. It is not a borrowing tool, but for the international spending that KOHO's card handles, it is usually cheaper.
7. PC Financial: Best for No-Fee Banking with Points
PC Financial offers no-fee everyday banking and earns PC Optimum points on purchases, which you can redeem for groceries and gas at participating stores. It suits KOHO users who mainly want a free daily account with rewards, though it does not provide a cash advance.
KOHO Cover Review: The Fees and Limits People Leave Over
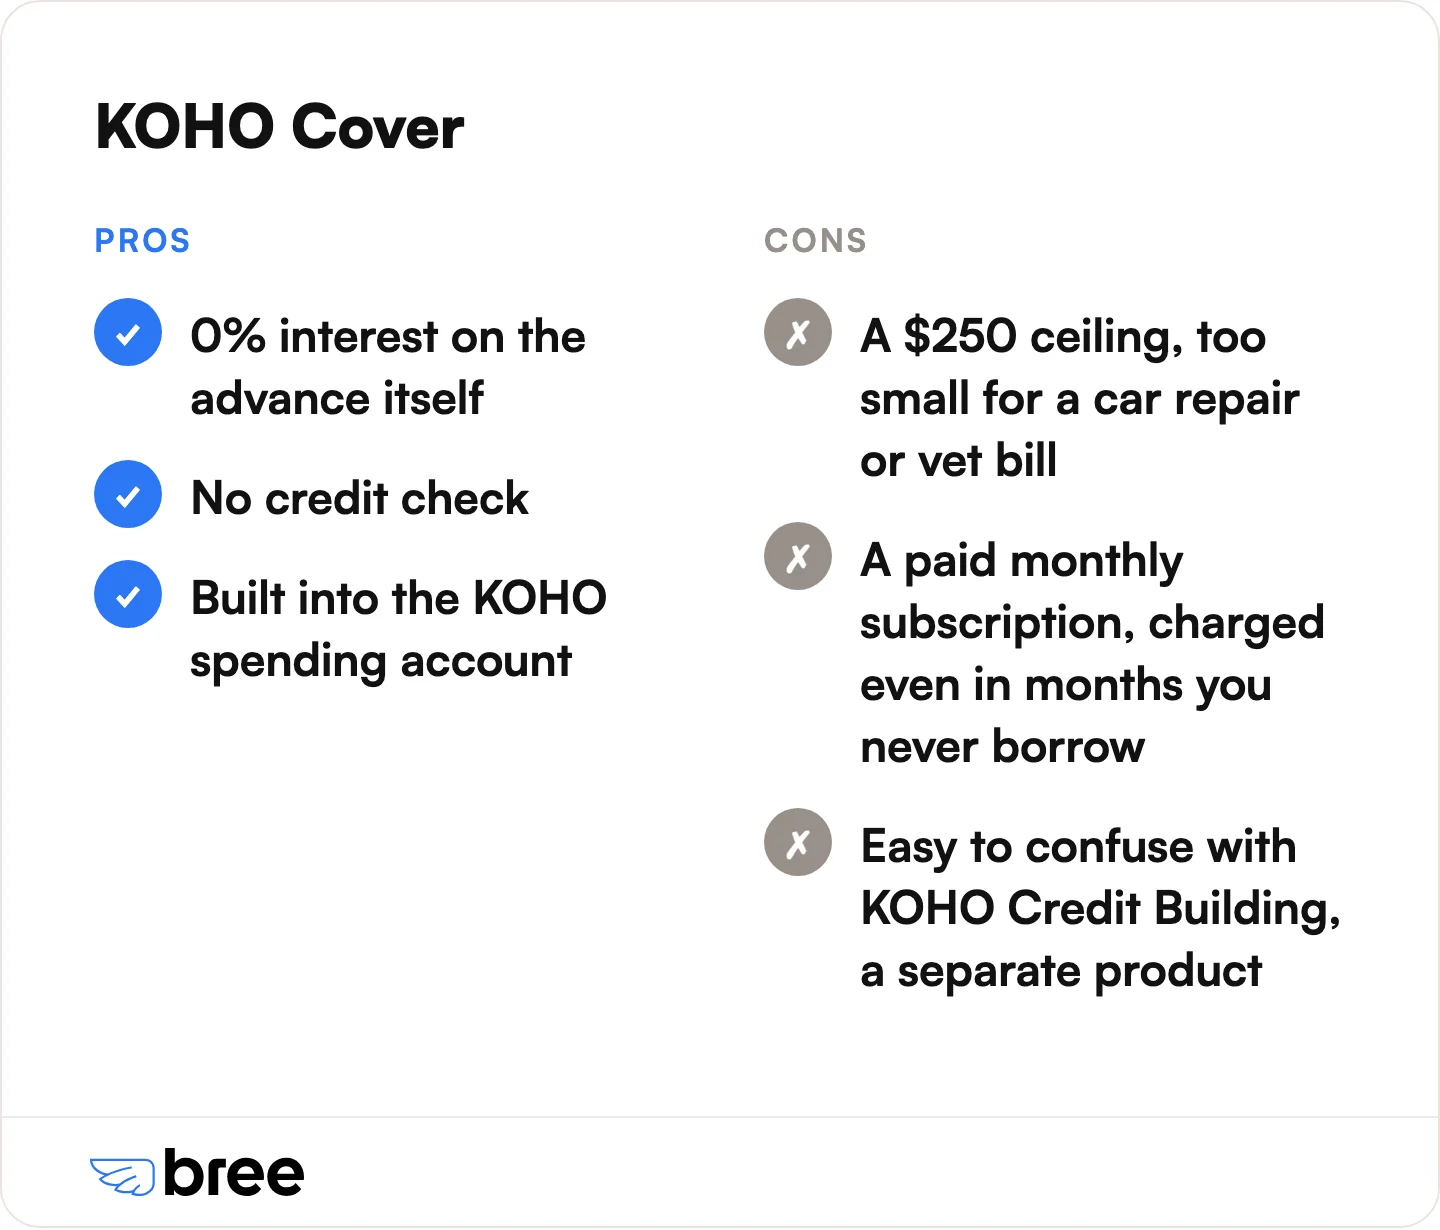
KOHO Cover is KOHO's version of an interest-free cash advance, built into the KOHO spending account rather than offered as a standalone app. It advances up to $250 to cover a shortfall, with 0% interest on the amount itself. The catch is in the structure around it. Cover is not a standalone advance; it is a paid monthly subscription you add to a KOHO account, so you carry a recurring fee for the option to borrow whether or not you use it in a given month. That is the opposite of an app that only costs you something when you actually take cash.
The bigger issue for many is the ceiling. At $250, KOHO Cover does not stretch far against a real emergency like a car repair or a vet bill, which is the single most common reason people look for a higher limit. KOHO Credit Building is also a separate product from Cover, which makes the two easy to confuse when you compare monthly costs.
Bree vs. KOHO Cover: A Cash-Advance Comparison
For the specific job KOHO Cover does, handing you cash before payday, Bree is the more flexible option. The difference comes down to how much you can borrow and what it costs to keep that option open.
The practical difference is that Bree charges nothing to keep the door open and gives you triple the limit, while KOHO Cover charges a monthly fee for a smaller advance tied to its own account. If you want the wider set of ways to cover a shortfall, our guide to payday loan alternatives lays them out.
Options to Avoid: Payday Loans and Credit Card Cash Advances
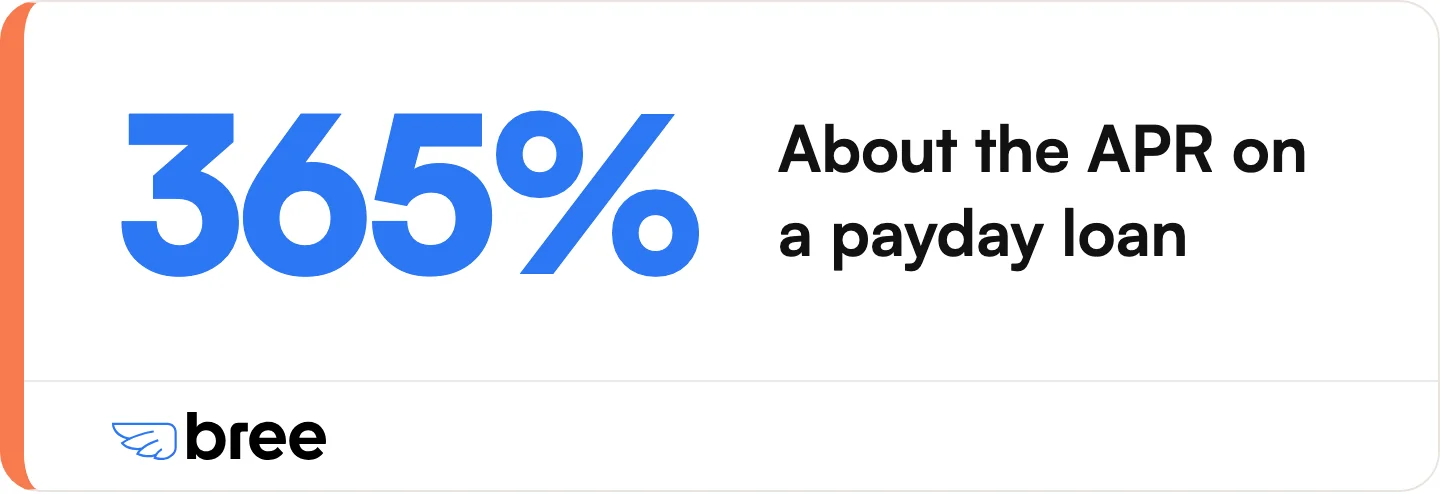
Payday loans are the most expensive way to cover a shortfall. Storefront and online lenders like Cash Money charge the federal maximum of $14 for every $100 borrowed, which works out to about 365% APR, and the loan is due in full on your next payday. That ceiling is set by federal law, and the high cost is what traps borrowers in a cycle of re-borrowing to cover the last loan.
A credit card cash advance is cheaper than a payday loan but still costly. Unlike a regular purchase, interest starts adding up the day you take the cash out, with no interest-free grace period, and there is usually a flat withdrawal fee on top. For a short-term shortfall, a free or flat-fee app costs far less.
How to Choose the Right KOHO Alternative
The right KOHO alternative depends on which job you are trying to fill. Match the pick to your goal.
- For interest-free funds before payday: Bree, with up to $750 at 0% and no credit check.
- For the largest interest-free amount: Bree, at up to $750, triple KOHO Cover's $250.
- For building your credit: Nyble, since it reports payments to Equifax.
- For the best savings rate: EQ Bank, with no monthly fee.
- For everyday cashback and rewards: Neo Financial or PC Financial.
- For banking and investing together: Wealthsimple.
- If you receive government benefits: Bree, which accepts ODSP, OW, CPP, EI, and CCB as income.
Frequently Asked Questions
What is the best KOHO alternative in Canada?
It depends on what you used KOHO for. If you want a cash advance before payday, Bree is the strongest alternative, with up to $750 at 0% interest and no credit check. If you want a better everyday bank or savings account, EQ Bank, Neo Financial, and Wealthsimple lead. KOHO does two different jobs, so the best replacement is the one that matches your reason for leaving.
Is there a KOHO alternative with a higher advance limit?
Yes. Bree offers up to $750, which is triple KOHO Cover's $250 limit, with no credit check and no mandatory fee, and it accepts government benefits as income. Nyble and KOHO Cover both cap at $250, so among interest-free apps Bree offers the most room for a real emergency.
What app will let me borrow money instantly in Canada?
Bree can send funds within minutes through its optional express delivery, sent as a direct deposit to your bank account. The free standard option arrives in one to three business days instead. There is no credit check either way, and you can request up to $750. For smaller amounts, our guide on how to borrow $50 instantly in Canada walks through the steps.
Is KOHO Cover really free?
No. KOHO Cover charges 0% interest on the advance itself, but reaching it still costs money. Cover is a paid monthly subscription you add to a KOHO account, so you carry a recurring fee for the option to borrow whether or not you take an advance in a given month. That is why many users prefer an app that only costs something when they actually borrow.
Do KOHO alternatives check your credit?
Bree does not, and neither do most cash advance apps, because approval runs on your banking activity instead of a credit pull. That also keeps a Bree advance off your credit file, so it never nudges your score in either direction. The exception on this list is Nyble, which reports to the bureaus on purpose so it can help you build a score.
Which is better for cash, Bree or Nyble?
For covering a bill, Bree is usually the better choice, because it offers up to $750 at 0% with no monthly fee. Nyble caps its line at $250 and puts instant funding behind a paid monthly plan, but it reports to Equifax, so it wins if your goal is building credit rather than borrowing more.
The Bottom Line
The best KOHO alternative comes down to which KOHO you are replacing. If you left for a better everyday account, EQ Bank, Neo Financial, Wealthsimple, and Wise each do one part of that job well. If you left because KOHO Cover's $250 limit and monthly fees did not add up, a dedicated cash advance app is the better fit.
Bree is the line of credit we built for exactly that gap. We offer up to $750 in funds at 0% interest with no credit check and no mandatory fee, we welcome government benefits as income, and every advance is a direct deposit to your bank account with up to 90 days to repay and no late fees. More than 600,000 Canadians already use it. If a genuine KOHO Cover alternative is what you came for, you can get up to $750 with Bree or read the full terms on our instant cash advance page.
Sources
- Financial Consumer Agency of Canada: Payday Loans
- Department of Justice Canada: Criminal Interest Rate Regulations
- Financial Consumer Agency of Canada: How Credit Cards Work
- Trustpilot: Bree Reviews
- Trustpilot: KOHO Reviews
- Trustpilot: Nyble Reviews

Join our newsletter to get the latest updates


