A payday loan in Alberta is a short-term loan of $1,500 or less that must be repaid within 62 days. Alberta law lets payday lenders charge up to $14 for every $100 you borrow, which works out to roughly 365% APR on a two-week loan. That makes it one of the most expensive ways to cover a shortfall between paycheques.
If you are searching for "payday loans near me," "no credit check payday loans," or "bad credit payday loans" in Alberta, there is a lower-cost option. You can borrow up to $750 at 0% interest, with no credit check and no late fees, and skip the payday fee trap entirely.
This guide covers what payday loans cost in Alberta, the rules and rights that protect you, how to check that a lender is licensed, and how an interest-free alternative compares.
Key Takeaways
- Alberta caps payday loan fees at $14 per $100 borrowed. A $500 payday loan costs $70 in fees, and a $1,500 loan costs $210.
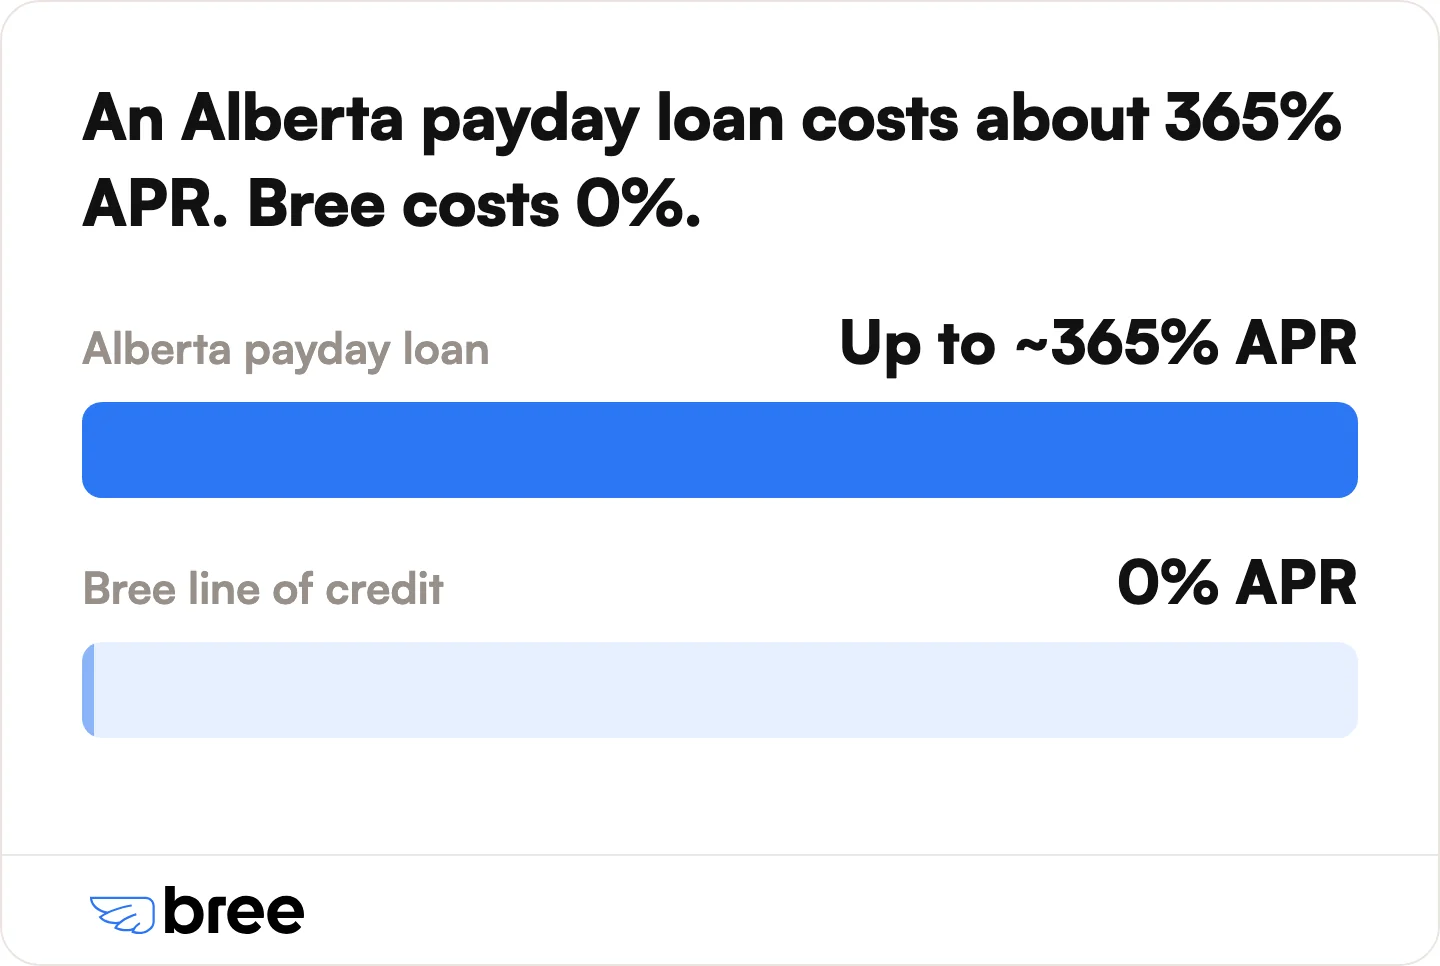
- That $14-per-$100 fee equals about 365% APR on a typical two-week loan, far above a credit card's 10% to 30% a year.
- Alberta borrowers are protected by provincial rules: a payday loan is capped at $1,500 over a maximum 62-day term, a lender cannot roll it over or extend it, and a dishonoured-payment fee is capped at $20.
- A bounced payday payment stacks up costs: a lender fee of up to $20, extra interest on the unpaid balance, and your bank's own NSF fee, now capped at $10 at federally regulated banks since March 12, 2026.
- Bree is an interest-free line of credit of up to $750 for Canadians between paycheques, with 0% APR, no credit check, and funds sent by direct deposit to your bank account.

What Are Payday Loans in Alberta?
Payday loans in Alberta are high-cost, short-term loans of $1,500 or less that must be repaid within 62 days, under the rules set by the Government of Alberta. They are sometimes called "quick loans" or "instant loans," and they are meant to cover an urgent expense until your next paycheque.
You usually repay the loan in a single payment, by giving the lender a post-dated cheque or authorizing a pre-authorized debit, so the full amount plus fees comes out of your account on the due date. If the payment does not clear, you can face extra charges.
Before you sign anything, read the loan agreement and make sure you understand the total cost and the repayment date.
How Much Do Payday Loans Cost in Alberta?
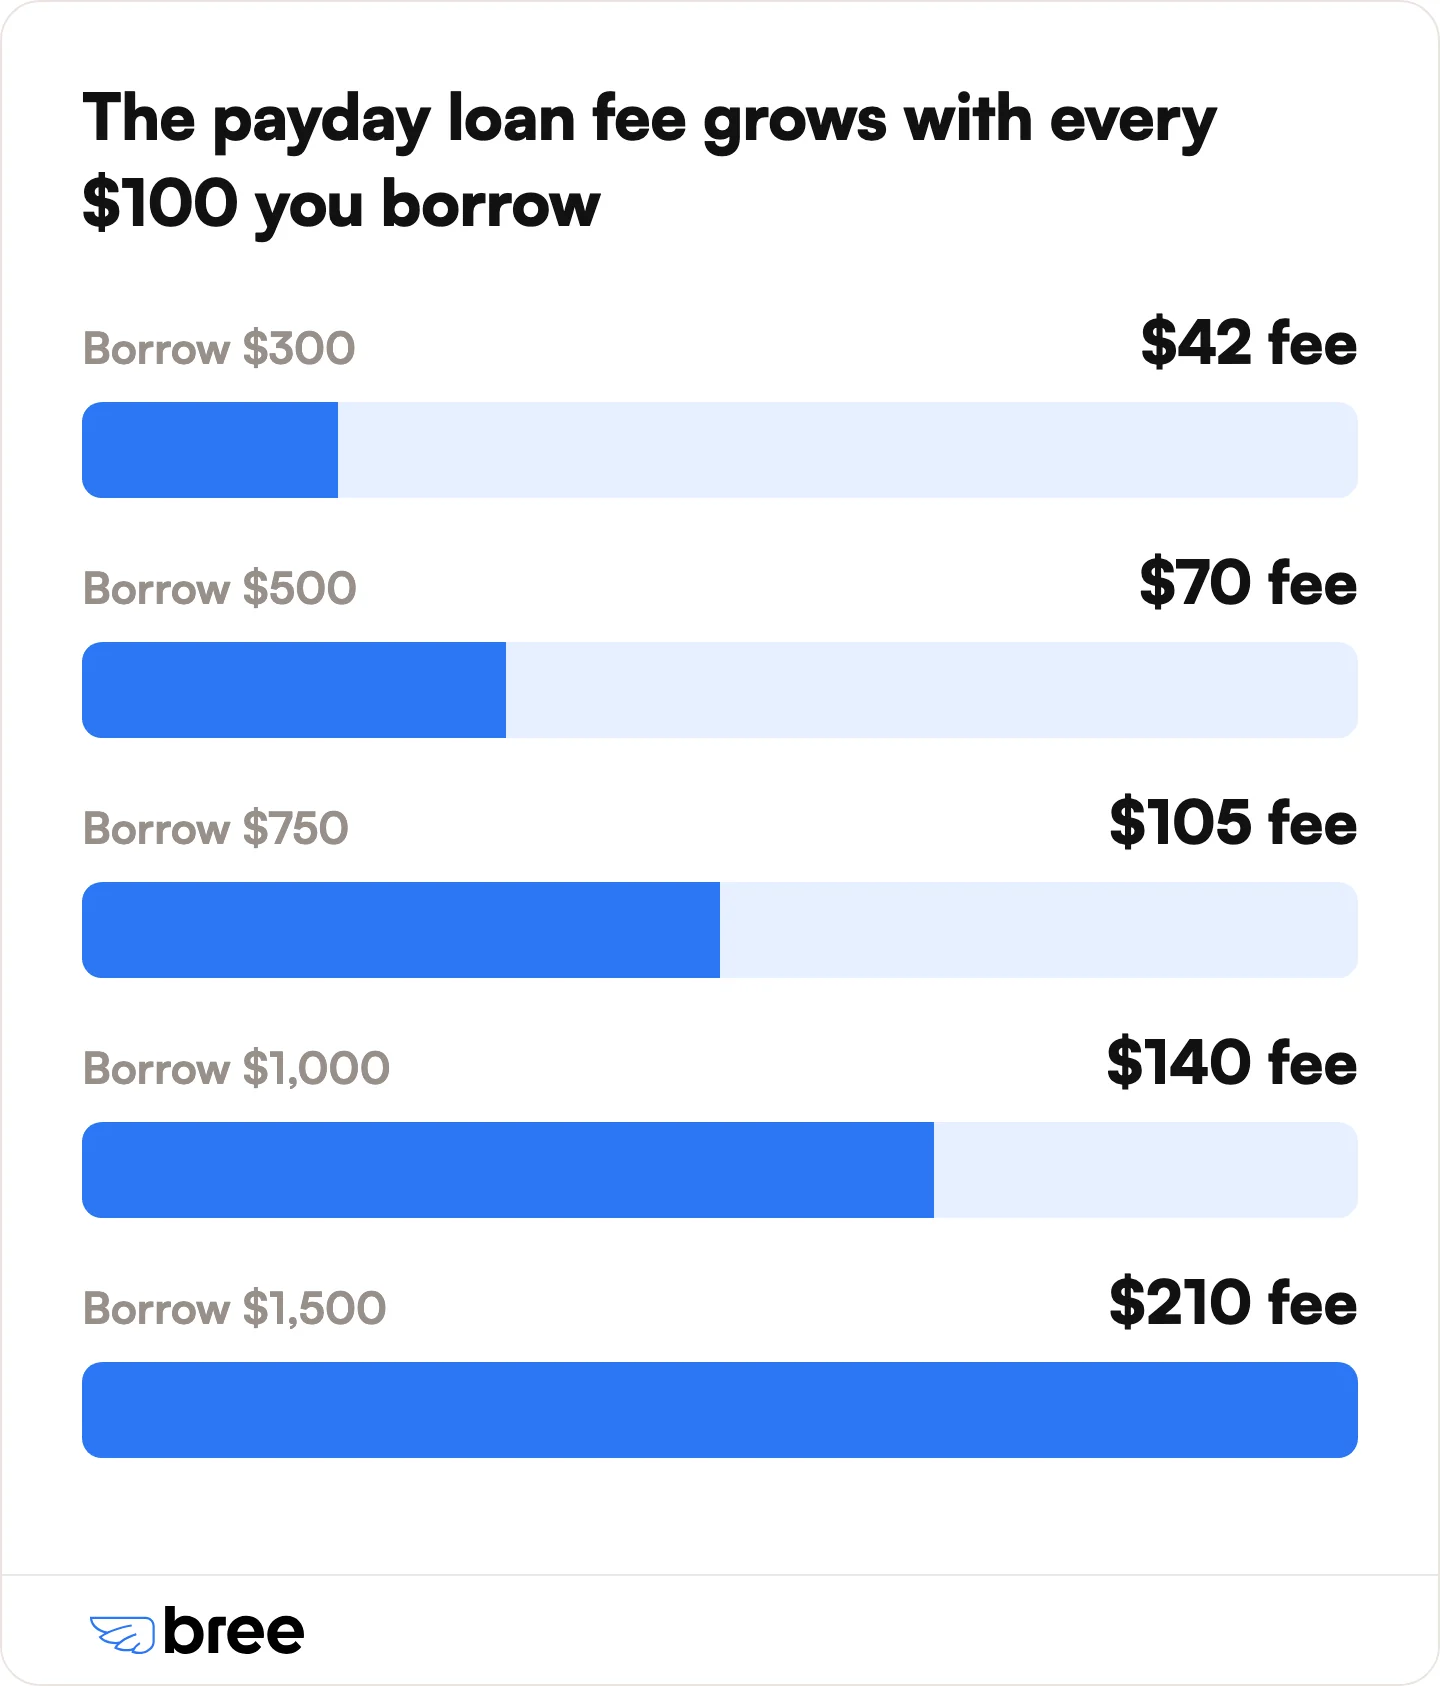
Payday lenders in Alberta can charge up to $14 for every $100 you borrow, including all fees and interest. This cap has applied since January 1, 2025, according to the Government of Alberta.
Here is what a payday loan costs at common amounts in Alberta:
That fee is far higher than it looks. A $14 charge on $100 borrowed for two weeks is 14% for 14 days, which annualizes to about 365% APR (14% multiplied by 365 days divided by 14 days). Stretched over the full 62-day term, the same $14-per-$100 charge works out to roughly 82% a year by that same calculation. For comparison, a credit card charges roughly 10% to 30% a year.
The real danger is the repayment squeeze. When $855 comes out of a $1,700 paycheque, you are left with little to cover rent, groceries, and bills, which is how many borrowers end up taking a second loan to get through the month.
If a payment does not clear, the costs stack up:
- A fee of up to $20 from the lender for a dishonoured cheque or pre-authorized debit.
- Extra interest and charges on the amount still owed, which the lender is allowed to add when a loan is not paid on time, according to the Government of Alberta.
- Your bank's own NSF fee, which is separate from the lender's charge. Federally regulated banks have capped this at $10 since March 12, 2026, according to the Financial Consumer Agency of Canada. Provincial credit unions are not covered by that cap.
Your Rights as an Alberta Payday Loan Borrower
Alberta law gives payday borrowers several protections, and knowing them can save you money. These rules are overseen by Service Alberta, which also licenses every payday lender in the province.
- A hard borrowing limit. No single payday loan can be more than $1,500, and the term cannot run longer than 62 days, according to the Government of Alberta.
- No rollovers or extensions. A payday lender cannot extend or roll over your loan, which means they cannot push back the due date and charge you a new fee, according to the Financial Consumer Agency of Canada.
- A capped missed-payment fee. If your cheque or pre-authorized debit is dishonoured, the lender can charge a one-time fee of up to $20 for that dishonoured payment.
- Licensed lenders only. Every payday lender operating in Alberta must hold a provincial licence, so you can confirm a lender is licensed before you borrow.
If a lender ignores any of these rules, you can file a complaint with Service Alberta.
How to Get a Payday Loan in Alberta (and Verify the Lender)
To get a payday loan in Alberta, you apply in store or online with a licensed lender and show that you have a steady income, a bank account, and a permanent address. Approval is usually fast, and most lenders do not run a credit check.
Before you borrow, confirm the lender is licensed. Every payday lender operating in Alberta must hold a provincial licence, and you can check a lender's status and read the province's annual payday lending report through the Government of Alberta and Service Alberta. An unlicensed lender is a warning sign, and borrowing from one leaves you without the protections above.
If you want to avoid payday fees altogether, it is worth comparing a licensed payday loan against a 0% alternative before you apply.
A Lower-Cost Alternative to Payday Loans in Alberta: Bree
Bree is an interest-free line of credit of up to $750 that gives Alberta residents a cheaper way to cover a shortfall than a payday loan. There is 0% interest, no late fees, no credit check, and no impact on your credit score. Funds are sent by direct deposit straight to your bank account, and you can use them for an unexpected bill, groceries, or to bridge the gap before your next paycheque.
Getting set up is done entirely online. To qualify, you need:
- A Canadian bank account
- Consistent income, including government benefits such as CPP, EI, and disability support
- A short review of your recent bank account activity instead of a credit check
Bree is free to use. The only costs are optional: a tip if you want to leave one, and an optional express fee if you need your money faster. Standard delivery is free and arrives by direct deposit within 1 to 3 business days. If you need cash in minutes, express delivery sends it to your bank account right away for a small fee. You repay on your own schedule, and you will see your terms before you accept. You can get started with Bree here.
If you specifically want funds delivered by e-transfer, see our guide to e-transfer payday loan alternatives in Alberta.
Payday Loans vs. Bree: Side-by-Side
The gap between an Alberta payday loan and a Bree line of credit comes down to cost and flexibility. A payday loan is faster to find on a street corner, but a Bree line of credit is far cheaper to repay.
Where a payday loan wins: quick in-person access and a higher ceiling of $1,500 if you need more than $750.
Where Bree wins: 0% interest instead of a $14-per-$100 fee, no late fees, no debt cycle, and repayment on your own schedule rather than a fixed payday deadline.
What to Do If You're Stuck in Payday Loan Debt
If you have taken on multiple payday loans and are caught in a cycle of borrowing, a debt professional can help you find a way out.
- Credit counsellor. A credit counsellor gives advice on budgeting, credit use, and getting out of debt. In Alberta, Money Mentors is a non-profit credit counselling agency, and you can also find a reputable counsellor through Credit Counselling Canada. Research any company before you commit, since there are both not-for-profit and for-profit counsellors.
- Licensed Insolvency Trustee. If you can no longer keep up with your bills, a Licensed Insolvency Trustee can assess your situation and recommend a solution. Trustees are federally licensed debt professionals who can administer legal debt relief such as a consumer proposal or bankruptcy.
Addressing the debt directly is almost always cheaper than rolling one payday loan into the next. For a step-by-step plan, see our guide to escaping the payday loan debt cycle.
Frequently Asked Questions
Can I get a payday loan in Alberta with no credit check or bad credit?
Yes. Most payday lenders in Alberta do not run a credit check, so people with poor or no credit can often qualify. The trade-off is the $14-per-$100 fee. A Bree line of credit also skips the credit check and approves you based on your recent bank account activity, at 0% interest.
What happens if I can't repay a payday loan in Alberta?
If your payment does not clear, the lender can charge a fee of up to $20 for the dishonoured cheque or pre-authorized debit, plus extra interest and charges on the amount still owed. Your bank may also add its own NSF fee, now capped at $10 at federally regulated banks. If you are struggling, contact the lender early, consider speaking with a credit counsellor, and read our guide to cutting NSF and overdraft fees.
Can I get a same-day or instant payday loan in Alberta?
Many Alberta payday lenders advertise same-day or instant funding, often within minutes to 24 hours. A Bree line of credit can also fund within minutes using express delivery, or free by direct deposit within 1 to 3 business days, without the payday loan fee.
Can I get a payday loan in Alberta on AISH or government benefits?
It depends on the lender, and many require employment income. Bree accepts government benefits, including CPP, EI, and disability support, as qualifying income, so Alberta residents on fixed benefit schedules can still get a line of credit of up to $750.
Are online payday loans legal in Alberta?
Yes, online payday loans are legal in Alberta as long as the lender is licensed and follows the $14-per-$100 cap and the other payday loan rules set by the Government of Alberta. Always confirm a lender's licence before you apply.
Conclusion
Payday loans in Alberta are capped at $14 per $100, but that still works out to roughly 365% APR on a two-week loan, and a single missed payment can pull you into a cycle of borrowing. Knowing your rights, from the $1,500 borrowing cap to the ban on rollovers, helps you avoid the worst of the cost.
There is a cheaper way to cover a shortfall. Bree is an interest-free line of credit of up to $750 for Canadians between paycheques, with 0% APR, no credit check, government benefits accepted, and a 4.8 out of 5 rating on Trustpilot from more than 8,000 reviews. Instead of paying $70 in fees on a $500 payday loan, you repay only what you borrow, on your own schedule. See how a Bree line of credit works or read reviews from other Canadians.
Sources

Join our newsletter to get the latest updates