Your rent is due in three days, but your Ontario Works payment does not land for another week. Traditional banks turn down most applications from people on social assistance, so a payday loan that accepts government benefits can feel like the only door left. It is not. You can borrow while on social assistance without a credit check, and you do not have to pay 365% interest to do it. This guide covers which lenders accept social assistance, what they really cost on a fixed benefit, and the cheaper options most people never hear about.
Key Takeaways
- Government benefits count as income. ODSP, Ontario Works, Employment Insurance, CPP and the Canada Child Benefit are accepted as qualifying income by many cash advance apps and payday lenders, which approve based on your bank deposits instead of your credit score.
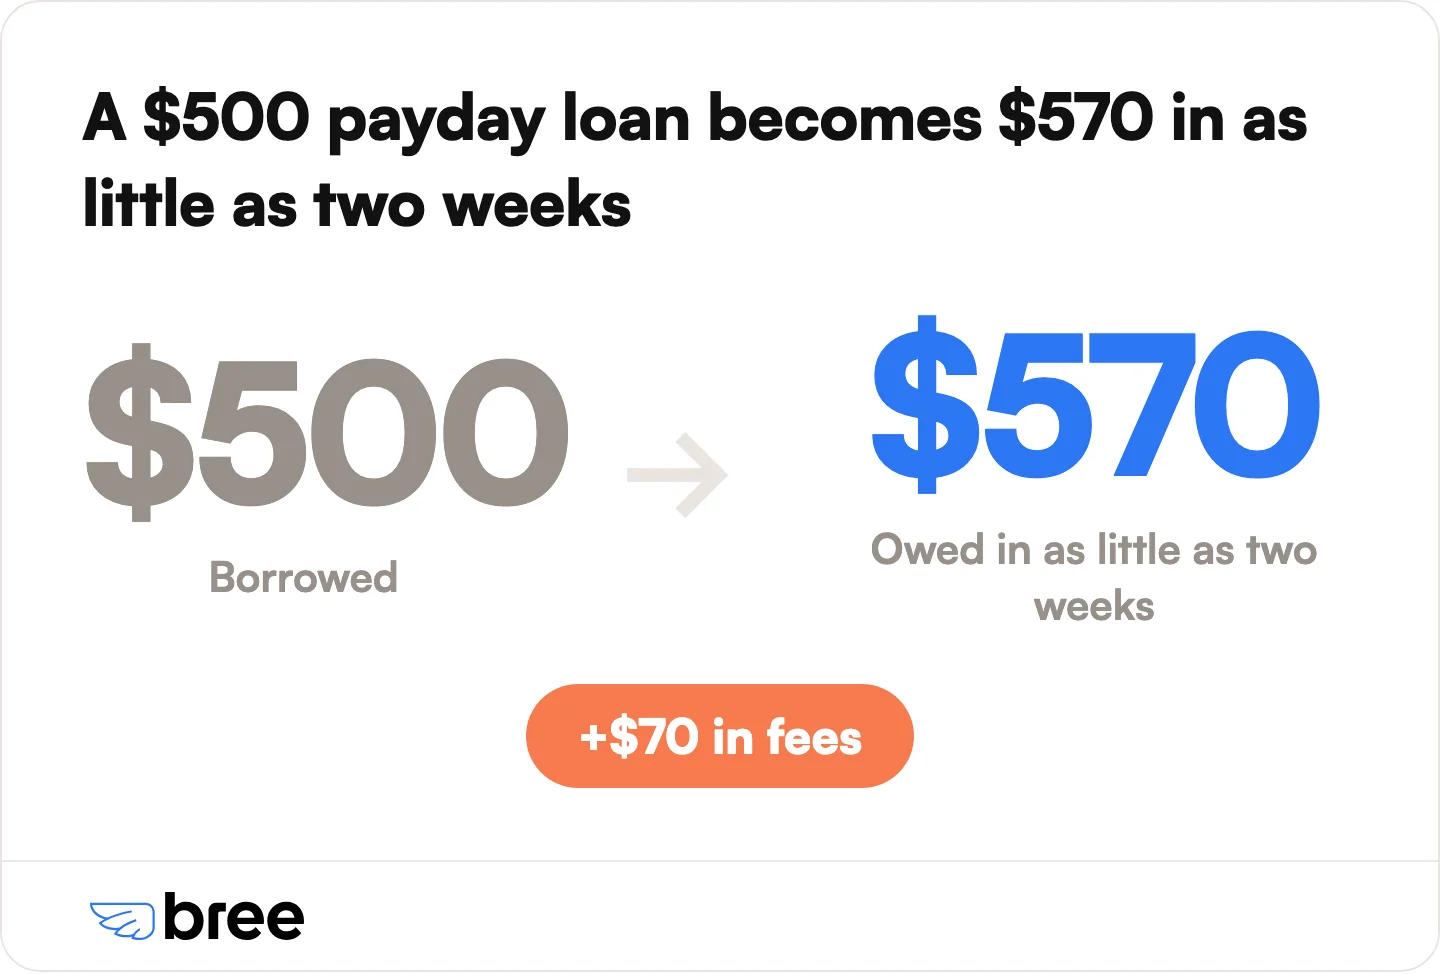
- Payday loans cost $14 for every $100 you borrow, about 365% a year. Borrow $500 and you owe $570 in as little as two weeks (Financial Consumer Agency of Canada).
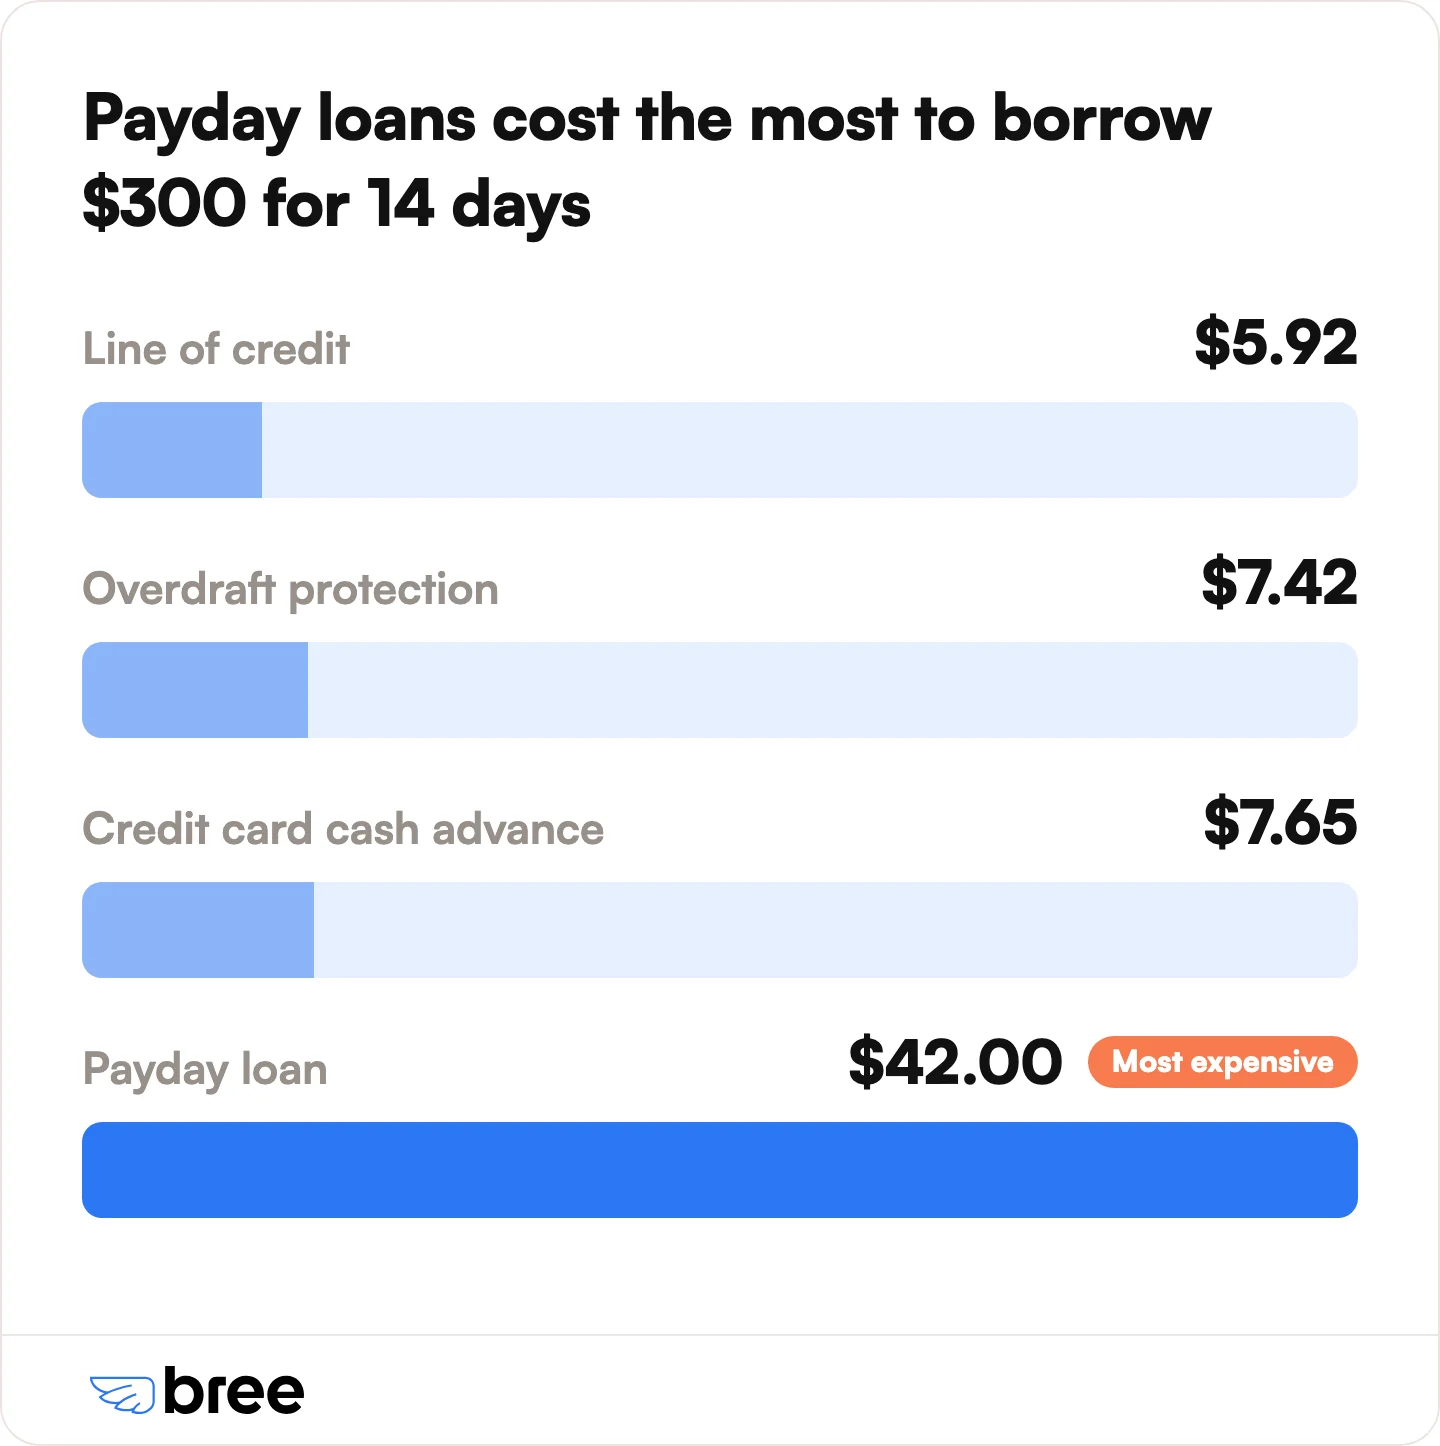
- A payday loan is the most expensive option on the shelf. Borrowing $300 for 14 days costs $42.00 through a payday lender, versus $5.92 on a line of credit (Financial Consumer Agency of Canada).
- An interest-free line of credit of up to $750 is the cheapest way to borrow, at 0% interest with no credit check, and it accepts government benefits as income.
- Bank NSF fees are now capped at $10, down from the $45 to $48 that was typical, on personal accounts at federally regulated banks since March 12, 2026.
- "Guaranteed approval" is a warning sign. No legitimate lender approves everyone. Approval depends on the deposits in your bank account.

Can You Get a Loan on Social Assistance in Canada?
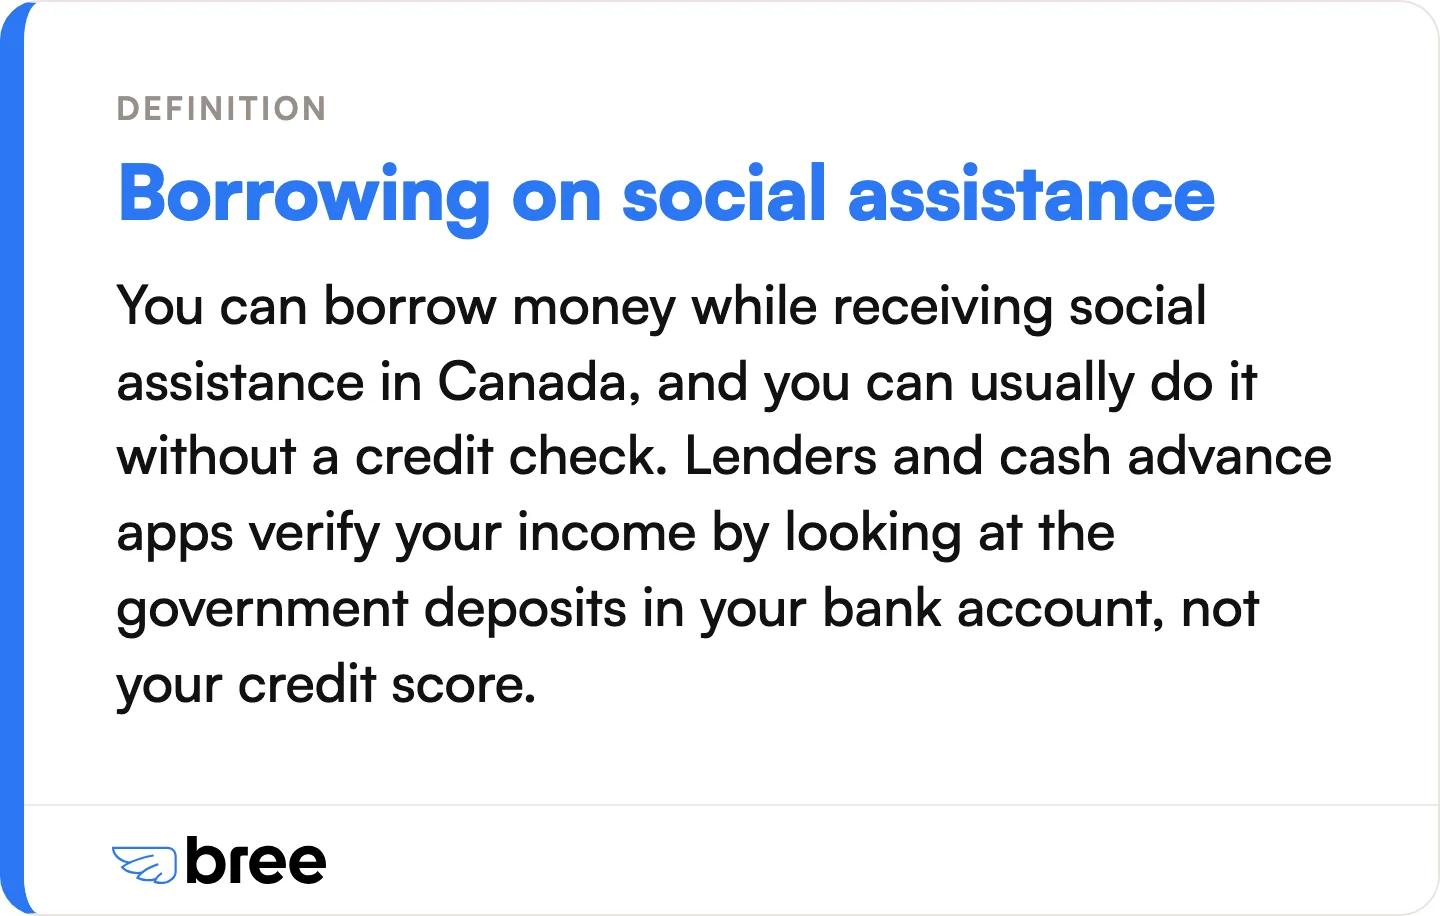
Yes. You can borrow money while receiving social assistance in Canada, and you can usually do it without a credit check. Lenders and cash advance apps that accept social assistance verify your income by looking at the government deposits in your bank account, not your credit score. Ontario Works, ODSP, Employment Insurance, CPP and the Canada Child Benefit all count as regular income.
The catch is cost, not eligibility. Payday lenders will accept your benefits and fund you fast, but they charge the most of any option. Cash advance apps and interest-free lines of credit accept the same government income for a fraction of the price. Because approval rests on consistent deposits rather than your credit history, a low credit score does not shut you out. Find out if you can get a payday loan while on EI.
Which Income Types Qualify (2026 Amounts)
Most lenders and cash advance apps that accept social assistance treat any steady government deposit as qualifying income. What matters to them is that the money arrives on a predictable schedule and adds up to enough to cover repayment.
Amounts come from the Government of Ontario, the Government of British Columbia and the Government of Canada program pages listed in Sources. Benefit rates are adjusted regularly, so check the official page for your program to confirm the current figure.
What Payday Loans Really Cost on a Fixed Benefit
A payday loan is the most expensive way to borrow while on social assistance. Canadian payday lenders charge $14 for every $100 you borrow, which works out to an annual rate of about 365% (Financial Consumer Agency of Canada). You can borrow up to $1,500 and have up to 62 days to pay it back.
Borrow $500 and the fee is $70, so you repay $570. When Ontario Works pays a single person up to $733 a month, that $70 fee is nearly a tenth of the entire cheque, money meant for rent and food.
The gap between a payday loan and every other option is stark. Here is what it costs to borrow $300 for 14 days, according to the Financial Consumer Agency of Canada:
Miss a payment and it gets worse. A payday lender can charge a one-time $20 fee for a dishonoured payment, on top of any fee from your bank. Bank NSF fees are now capped at $10 on personal accounts at federally regulated banks, down from the $45 to $48 that was typical, under federal rules that took effect March 12, 2026. In provinces and territories without specific payday loan rules, the maximum cost of borrowing is the 35% criminal interest rate, about $1.35 per $100 over two weeks.
Your Options, Ranked Worst to Best
You have several ways to borrow while on social assistance. Here they are ranked by what they actually cost, from the most expensive to the cheapest.
3. Payday loans (last resort)
Payday lenders such as Money Mart and Cashco accept government benefits and fund fast, usually by e-transfer, but they are the most expensive option on this list. At $14 per $100, about 365% a year, a payday loan traps borrowers who cannot repay the full amount plus the fee within two weeks. Use one only when nothing else is available.
2. Personal and installment loans (a cheaper middle ground)
Installment lenders such as Magical Credit lend larger amounts, into the thousands of dollars, over several months at mid-range interest rates, and they accept a wide range of government income. They are far cheaper than payday loans but still carry real interest, so they fit a larger, planned expense better than a small gap before your next benefit payment.
1. Interest-free lines of credit and cash advance apps (best value)
Cash advance apps and interest-free lines of credit are the cheapest way to bridge a short gap on social assistance. Three of them accept government benefits as income:
- Bree is an interest-free line of credit of up to $750 at 0% interest, with no credit check and no mandatory fees.
- KOHO Cover offers $20 to $250 at 0% interest through a paid monthly subscription.
- Nyble offers up to $250 at 0% interest, with a paid monthly subscription for instant funding and free slower delivery.
Bree covers the largest amount of the three and charges nothing to borrow.
Why Bree Works for Social Assistance Recipients
Bree is an interest-free line of credit built for Canadians who need to bridge a short gap between payments, and we accept government benefits as income when most lenders will not. You can access up to $750 at 0% interest, with no credit check, no late fees and no mandatory fees. ODSP, Ontario Works, CPP, the Canada Child Benefit and EI all qualify as income.
Funds arrive by direct deposit to your bank account. Standard delivery is free and takes one to three business days. Optional express delivery puts the money in your account within minutes for a small fee. You repay on your own schedule, and you see your terms before you accept.
Bree is free to use, and we make money from optional tips, the way you might tip a waiter. There is no interest and no mandatory fee to borrow. Bree holds a 4.8 out of 5 rating on Trustpilot from more than 8,000 reviews, and over 600,000 Canadians now use it. Availability can vary by province, so check the app to confirm Bree covers where you live.
See if you qualify for up to $750 with Bree.
Do You Qualify? (Probably Yes)
Most cash advance apps and lenders that accept social assistance approve you on your bank deposit history, not your credit score. If your government benefits land in your account on a regular schedule, you have a strong chance of approval.
Basic requirements are simple:
- 18 years or older
- Canadian resident
- An active bank account that receives your benefits by direct deposit
- Enough regular income to cover repayment
Bree looks for about $1,200 a month in consistent deposits across your last two months of bank history. ODSP, or benefits combined with part-time work, usually clears this. Ontario Works on its own can fall short of it, so combining income sources helps. If you are on disability, our guide to payday loans that accept BC disability covers what qualifies in that case.
No credit check does not mean guaranteed approval. Any lender promising guaranteed approval to everyone on social assistance is a warning sign, because approval always depends on the money moving through your account.
How to Apply in 5 Minutes
Applying takes a few minutes online, whether you choose a cash advance app or a payday lender.
- Compare the cost first. A 0% line of credit and a 365% payday loan both approve you fast. The price difference is enormous, so start with the cheapest option.
- Fill in the application. Provide your name, address, email, phone number and bank account details.
- Connect your bank account. An automated check confirms your social assistance deposits. There is no manual paperwork and no faxing pay stubs.
- Get a decision. Approvals usually arrive within a few minutes, based on your benefit deposits and your capacity to repay.
- Receive your funds. Payday lenders usually send an Interac e-transfer within 15 to 30 minutes. With Bree, funds arrive by direct deposit to your bank account: within minutes on optional express delivery, or free within one to three business days. For more on how delivery works, see our guide to e-transfer loans on social assistance.
Before You Borrow: Free Help First
Before you borrow anything, check whether you can get the money for free. Several programs help Canadians on social assistance cover an emergency without a loan at all.
- 211 Canada connects you with emergency financial help, food banks and housing support at no cost. Call 2-1-1 or visit 211.ca.
- Provincial hardship supplements. Ontario Works and many provincial programs offer extra help for one-time costs like medical needs, moving expenses or a utility deposit. Ask your caseworker.
- Family or friends. An informal loan avoids interest and credit checks entirely.
- Credit unions. Some offer small emergency loans at 12% to 18%, far below payday rates.
- A credit card cash advance is expensive but still cheaper than a payday loan. Interest starts the day you take it out, with no grace period, and the rate is higher than for purchases. On the Financial Consumer Agency of Canada example above, a $300 credit card cash advance for two weeks costs $7.65, against $42.00 for a payday loan.
How to Avoid the Debt Trap
The payday loan debt trap starts when you cannot repay the loan plus its fee by the due date, and on a fixed benefit that happens quickly. When $733 a month has to cover rent, food and everything else, finding $570 to repay a loan in two weeks is often impossible.
So people take out a new payday loan to pay off the old one. The balance never drops, and the fees repeat every cycle. It is how a single $500 shortfall turns into hundreds of dollars in charges over a few months.
Three habits keep you out of it: borrow only what you can repay, choose a 0% option over a 365% one, and never take a new loan to pay off an old one. If your shortfall is really a timing problem, knowing your exact ODSP payment dates or checking whether you can get payday loans on Ontario Works can help you plan around the gap instead of borrowing through it.
Frequently Asked Questions
Can you get a loan on social assistance in Canada?
Yes. You can borrow while on social assistance, usually without a credit check. Cash advance apps and payday lenders verify your government deposits instead of your credit score, so ODSP, Ontario Works, EI, CPP and the Canada Child Benefit all count as income.
Who will give you a loan when no one else will?
Lenders that assess income by bank history, rather than credit score, are the most likely to approve you. An interest-free line of credit like Bree, cash advance apps like KOHO and Nyble, and installment lenders like Magical Credit all accept government benefits and approve without a hard credit check. Avoid anyone advertising guaranteed approval.
Which app lets you borrow money instantly on social assistance?
Bree lets you borrow up to $750 and, with optional express delivery, sends the funds to your bank account within minutes. It accepts ODSP, Ontario Works, CPP, the Canada Child Benefit and EI as income, and it runs no credit check.
Where can you get a loan if you are on benefits?
Your options on benefits fall into a few groups: an interest-free line of credit like Bree, cash advance apps like KOHO and Nyble, installment lenders such as Magical Credit, and payday lenders such as Money Mart and Cashco. Ranked by cost, a 0% line of credit like Bree is the cheapest and a payday loan the most expensive.
How much can you borrow on social assistance?
Amounts depend on the lender and your income. An interest-free line of credit like Bree goes up to $750, while cash advance apps like KOHO Cover and Nyble reach $250. Payday loans run $100 to $1,500, though first-time borrowers usually get $300 to $800. Installment loans go higher, into the thousands of dollars.
Are e-transfer loans available for social assistance recipients?
Yes. Many payday lenders fund recipients by Interac e-transfer within 15 to 30 minutes. Bree instead uses direct deposit to your bank account, within minutes on express delivery or free in one to three business days. Both approve on your income, not your credit.
What happens if you cannot repay a loan on social assistance?
Contact your lender right away. A payday lender can charge a $20 fee for a dishonoured payment and send the debt to collections, and your bank may add an NSF fee, now capped at $10 on personal accounts at federally regulated banks. Bree charges no late fees. Never take out a new payday loan to cover an old one.
The Bottom Line
Being on social assistance does not shut you out of emergency cash, and it does not mean paying 365% for it. Payday loans that accept social assistance approve you fast, but they cost $14 for every $100, enough to swallow a tenth of an Ontario Works cheque in fees. Cheaper options accept the same government income and cost a fraction as much.
Bree is the interest-free line of credit we built for Canadians between payments, including those on ODSP, Ontario Works, CPP, the Canada Child Benefit and EI. You can borrow up to $750 at 0% interest, with no credit check and no mandatory fees, and repay on your own schedule. See if you qualify for up to $750.
Sources
- Financial Consumer Agency of Canada: Payday loans
- Financial Consumer Agency of Canada: How credit cards work
- Financial Consumer Agency of Canada: New NSF fee regulations
- Government of Ontario: Ontario Works
- Government of Ontario: Ontario Disability Support Program
- Government of Canada: EI regular benefits, how much you could receive
- Government of British Columbia: Income assistance rates
- Government of Ontario: Payday loans, your rights
- 211 Canada

Join our newsletter to get the latest updates